


Chinese Mainland
ONE BELT ONE ROAD
By BDO Singapore
“This initiative will directly affect 4.4 billion people with a collective GDP of US$2 trillion once completed.”
The “One Belt One Road” (OBOR) initiative was announced by President Xi Jinping of China in 2013. This initiative was brought forth during his visits to Kazakhstan and Indonesia in 2013, when he formally announced the Silk Road Economic Belt and the 21st Century Maritime Silk Road initiatives. This subsequently became a vital foreign policy for China in many aspects, mainly with the intention of promoting economic cooperation amongst countries along the “Belt” and “Road” routes.
Please click to read the full article.
Editor's picks
Trending articles
Can Exporting Industrial Capacity Rescue the Chinese Economy?
By China-United States Focus
In 2015, the Chinese government unveiled a new slogan – “industrial capacity cooperation” – as it pursued trade and investment deals abroad. At the time, the Chinese economy was headed for serious trouble, with manufacturing profits dropping and worrisome bubbles preparing to burst in domestic financial markets. In essence, China now seeks to export its excess industrial capacity as a means to cope with its economic troubles. On the one hand, this is a strong sign that China is becoming a mature industrial power, following in the footsteps of nations like the United Kingdom and the United States before it. Yet global economic conditions suggest that China may not be able to export its way out of the present crisis.
A country exports its industrial capacity when it invests industrial capital – factories, machinery, and so on – overseas. For example, a Chinese firm might open a factory in Ethiopia with its own money and machinery. We can tell that China is trying to export its excess capacity by examining the international deals and statements that the Chinese government has made over the past year. In May 2015, the Chinese government announced a $70 billion plan to export spare capacity from industries including railway construction and telecommunications technology. Officials and state news agencies heralded the new plan during a Latin American tour that included stops in Brazil, Chile, Peru, and Colombia. Further ventures were announced throughout the year in countries as far apart as Ethiopia and Kazakhstan. Recently, China signed a memorandum of understanding with Saudi Arabia pledging to jointly pursue China’s One Belt, One Road (OBOR) initiative, including industrial capacity co-operation.
The industries China has highlighted as key priorities for its industrial capacity co-operation initiatives are those that suffer from chronic overcapacity problems: steel, construction materials, electrical power infrastructure, and rail manufacturing. During its economic rise in recent decades, China became the globe’s preeminent manufacturer of many of these industrial commodities. Now, global demand simply cannot keep up with China’s capacity to produce goods like steel, leading to a steep decline in prices. By exporting excess industrial capacity that simply cannot profitably produce in domestic conditions, China may hope to relieve some of the pressure on its industries.
Of course, investing capital abroad will help China increase its international influence. Exporting industrial capacity is a key component of Chinese initiatives like OBOR and the new Asian Infrastructure Investment Bank (AIIB), and most countries are more than happy to welcome Chinese investment. If Chinese construction equipment cannot be put to use in China, it can be used in Central Asia to develop infrastructure that will open markets to Chinese goods and allow further penetration of local economies.
Exporting both excess commodities and industrial capital is a classic strategy that developed economies use to cope with saturated markets and diminished opportunities for investment at home. Lenin famously argued that the struggle to export excess capacity motivated imperialism in the late 19th and early 20th centuries. Both the United Kingdom and the United States followed this path as they rose to global prominence, becoming creditor nations that dispensed industrial and financial capital around the world. Where economic power led, political influence often followed; where capital could not enter on its own, armed force opened the way.
Given these historical precedents, China’s transformation into a capital-exporting economy suggests that it is maturing as an industrial power and that its international influence will continue to expand. China and today’s United States occupy remarkably similar positions to yesteryear’s United Kingdom and a rising United States in the early 20th century, albeit with some notable differences. Foreign investment is still extremely asymmetric, with developed nations far outspending their developing counterparts. From 1980 to 2008, the foreign direct investment of firms from the advanced capitalist economies (the U.S., Europe, and Japan) grew from $500 billion to nearly $14 trillion. By the end of this period, the foreign employment and sales of these companies exceeded their domestic numbers. Firms from developing countries also increased their foreign investments, but these totaled up to less than a fifth of the advanced countries’ investments. The Netherlands, a country of only 16 million people, had more investments abroad than Brazil, Russia, India, and China combined.
Despite its implications for China’s international power and prestige, there is good reason to be skeptical that exporting excess capacity will rescue the Chinese economy in the short term. As I have written in earlier articles, today’s economic troubles reflect unique structural conditions that are unlikely to disappear without some kind of major destruction and devaluation of global capital.
The problem is that China is trying to export its way out a local crisis caused in large part by a global glut of commodities. Moving excess industrial capacity abroad will do little to alleviate the fact that the global supply of many key goods is now far in excess of demand unless those local markets happen to be heavily protected from international dynamics. Given that countries like Brazil, a key Chinese partner, are also experiencing collapsing prices, it is hard to believe that there are many suitable outlets for this strategy. Put simply: Building Chinese-owned factories in Brazil may not be particularly profitable if no one buys what they produce.
Like its historical peers, China is starting to mature as an economic powerhouse. However, it is coming of age in a time of severe economic turbulence and uncertainty. It remains to be seen how China’s rise will be impacted by the difficult conditions of the present day. Whatever the case, we should expect Chinese foreign investment to continue to grow, spurring a commensurate rise in its political influence.
Please click to read the full article on the website of China-United States Focus.
Editor's picks
Trending articles
Connecting the World Through “Belt & Road”
By China-United States Focus (He Yafei, former Vice Minister, State Council Office of Overseas Chinese Affairs)
China’s One Belt, One Road (OBOR) initiative has been gaining attention since its proposal by President Xi Jinping in 2013, along with the recent Asia Infrastructure Investment Bank and the Silk Road Fund.
OBOR has been proposed as an innovative method of co-operation in global governance in the face of a worsening economic climate and simmering geopolitical problems worldwide. This solution follows eight years of slow recovery since the financial crisis of 2008, which arguably witnessed the failure of “neo-liberalism” and its infamous economic reform recipe enacted by the “Washington Consensus.” China’s economic growth might give the world its only hope, with an annual GDP increase of 7% that contributes over 30% to global economic growth.
The dire prospects for global development and the re-emergence of geopolitical troubles in the Middle East, Ukraine and elsewhere are pressing for elusive answers. What should we do to promote global peace and common development in the age of fast-paced globalization? Given the reality of the world today, what is so innovative and trailblazing about OBOR? Can it really offer a way out of the quagmire in which the world finds itself? I will try to illustrate my points as follows.
First, founded in the idea of building a new network of global partnerships, OBOR provides a fresh way of thinking about regional and global co-operation, by including both bilateral and multilateral co-operation in political, economic, cultural and other fields. It emphasizes the adaptability of development strategies in China and other participating nations, in order to produce benefits that are shared by all in an economic “win-win” outcome.
In a nutshell, OBOR envisions the creation of multiple economic corridors encompassing more than 60 countries in East Asia, Southeast Asia, Central Asia, South Asia, West Asia, North Africa and East Africa, linking the most dynamic East Asia Economic Zone with the advanced European Economic Zone. If we visualize OBOR, it is an economic partnership map with multiple interconnected rings. President Xi describes OBOR as a “chorus”, not a soloist singing. OBOR transcends different Free Trade Agreements (FTAs), including the newly concluded TPP, in both scale and content. It envisions regional integration beyond pure economic union, forming a political community founded on common interest in an attempt to forge, as much as possible, a common cultural identity.
Second, OBOR looks to build “five connectivities” with a view of creating a community of nations with a common destiny. These “five connectivities” include policy consultation, infrastructure connectivity, free trade, free circulation of local currencies, and people-to-people connectivity. In sum, these connectivities denote the “big trends” in economic globalization and socialization, the information revolution, and shared economic growth.
Policy consultation is placed first in the OBOR plan, because its success depends on the participants’ adoption of parallel development strategies and policies. Regular policy consultations align participants’ economic growth strategies, macro-economic policies, and major growth plans. The importance of infrastructure connectivity is easily understood, since OBOR’s economic growth and regional economic integration depends on the sophistication and connectivity of both “hard and soft” infrastructures.
Free trade is necessary for OBOR in that Asia as a whole needs to upgrade its place in global production and value chains, with a freer and more integrated production network that embraces individual countries’ advantages. Free trade should also come into play with regional production capacity realignment, i.e., moving excessive production capacity to countries that are in need to build up their own economic frameworks. The end result will be a more open regionwide economic system.
Free circulation of local currencies will be integral to the new economic structure OBOR creates. The Asia Infrastructure Investment Bank (AIIB) and the Silk Road Fund have shown the way to global financial system reforms and offer a new avenue of infrastructure investment funding. According to the Asia Development Bank, from 2010 to 2020 there was an $800 billion gap in Asia Infrastructure funding. Mackenzie Consultancy estimates that over the next two decades the global need for infrastructure funding will amount to a staggering $57 trillion. Intraregional free trade and infrastructure funding will enable a more efficient use and circulation of currency in the involved countries, thus reducing or avoiding the risks associated with a complete dependency on a U.S. dollar-centered financial system for project funding.
People-to-people connections result from more frequent exchanges at all levels and create a common cultural identity and affinity that will go a long way in providing a solid social foundation for building OBOR. People will only accept and engage with OBOR when they get to know other ethnic groups better.
Third, OBOR is not only a great opportunity for China to further her opening-up and reform, it also provides a large, multi-layered platform all countries along OBOR can use to reap greater economic and social benefits by opening up to one another. It is clear that China will be one of the major economic engines in the first half of the 21st century, with projected outward investments of $500 billion and over 500 million outbound tourists in the next five years. “Made-in-China,” Chinese capital, China’s market, and Chinese consumers will be hallmarks in the new round of worldwide economic growth.
Fourth, OBOR will be the cushion for China and the United States, as rising and incumbent powers seek to avoid falling into the proverbial “Thucydides Trap”: The Belt and Road initiative will help both nations in a profound manner to have an appropriate strategic assessment of each other’s intentions, by showing China can create solid co-operation in a strategically significant region. OBOR is also useful, as it involves both countries in policy consultation and economic collaboration, shaping the future of our bilateral relations.
I am happy to note that after the historic visit to the U.S. by President Xi, President Obama’s administration has reversed its position on OBOR and the related AIIB, adopting a more open and welcoming attitude. This year, as we celebrate the 70th anniversary of the founding of the United Nations, all nations big and small are reminded that it is necessary to improve the current global governance system. I am convinced that with joint efforts and determination, OBOR will prove its worth to China and its participants, including the United States, as a new path to mutual trust and a better future in global governance.
Please click to read the full article on the website of China-United States Focus.
Editor's picks
Trending articles
China’s ‘Belt and Road’ Initiative: Opportunities for Investment in Africa Infrastructure
By Tom Luckock (Norton Rose Fulbright)
China's ‘Belt and Road’ initiative – the flagship foreign policy of President Xi Jinping – has the potential to open a raft of new development opportunities for African infrastructure, mining and power projects. The extent to which the initiative covers Africa is still a little unclear but it appears to cover North Africa and parts of East Africa at the very least, with Kenya acting as the gateway to the initiative’s links to Africa through its modern ‘Maritime Silk Road’.
Although the practical application of the initiative is still developing, to date we are seeing greater focus by Chinese SOEs on countries subject to the initiative, shorter and easier outbound approvals and easier credit approvals within Chinese banks. Chinese SOEs have been preparing business plans for investment in the Belt and Road projects and countries, as well as demonstrating progress against those plans internally. Chinese companies will insert long explanations on links to the Belt and Road in all of their approval applications. One immediately obvious consequence is the number of previously shelved projects being dusted off and started again as part of The Belt and Road Initiative.
The key opportunity for non-Chinese sponsors is to tap Chinese capital for The Belt and Road projects in North and East Africa. One way is by working with a Chinese EPC contractor to bring in Chinese banks and Sinosure cover.
There are a number of issues to think about when tapping Chinese funding, including the following:
The Chinese EPC contractor is the key route to the banks
It is important to remember that the contractor, not the borrower/sponsor, is the bank’s customer. That means using the contractor to obtain good financing terms and overcome negotiation obstacles.
Establish finance support up-front
Contractors frequently promise finance on attractive terms, but the key is to understand the substance to that support as early as possible. Many projects stall when credit approval falls through late in the day.
To the extent possible key finance terms should be agreed up-front
Negotiate key points, such as pricing, parent support, and change of control, up front when the contractor is competing hard for the project. This is not always easy to achieve but on some occasions sponsors have stapled a finance term sheet to the back of terms agreed with the contractor.
China Inc. and information flow
The sponsor will be surrounded by Chinese kit, EPC, debt and export credit cover. Information flows freely within China Inc. but does not flow so freely across to a foreign sponsor. It’s important to be aware of this.
Maintain competitive tension as long as possible
Chinese negotiations can drag and sometimes an EPC contractor will pull out because of unexplained outbound or state owned asset approvals difficulties, or because of credit approvals issues. Maintaining competitive tension as long as possible avoids the downside if this occurs and also keeps the pressure on the Chinese contractor.
Keep documents and structures simple
As far as possible, use structures that have been approved and negotiated before, as these can typically be negotiated and approved much more quickly. New structures are possible, particularly for strategically important projects, but the contractor, as the bank’s customer, will need to assist to push these through.
Partnering with foreign sponsors is a key aspect of The Belt and Road initiative. This is an important aspect to being sensitive to host country concerns, diversifying risk for China and also an important element to China's SOE reforms which aim to see China's SOEs partnering with the private sector. It also should in theory reduce some of the moral hazard concerns that SOEs with strong policy support may build projects that don't need to be built.
This article was first published by Norton Rose Fulbright and is reprinted here with their full permission.
Please click here for the original article.
Editor's picks
Trending articles
Tapping Chinese Belt and Road Capital for Power Projects: Ten Things to Know
By Norton Rose Fulbright
China’s Belt & Road Initiative (B&R) could see up to USD1.5 trillion invested in the 60 countries that comprise the B&R. This will make China the largest funder of power in the region. The sweet spot for Chinese banks, contractors and equipment suppliers, is difficult jurisdictions like those that make up the B&R – in these countries Chinese pricing of kit and debt is competitive, funds are deployed relatively quickly and importantly, Chinese capital comes with a partial fix for host country political risk. For any investor in emerging power markets, Chinese capital cannot be ignored. In this outline we look at how to tap it ……
This article was first published by Norton Rose Fulbright and is reprinted here with their full permission.
Please click here for the full article and related information (in Chinese).
Editor's picks
Trending articles
China’s New Silk Route - The Long and Winding Road
By PwC’s Growth Markets Centre
February 2016: Over the past year China has increasingly made headlines in global news, creating a constant stream of articles, background reports and opinion pieces. Many of the events covered are having an impact well beyond the country and its own economy. Some of the main events that have dominated global news recently have included the ongoing slowdown of the Chinese economy, culminating in the slowest annual growth in 25 years, several severe stock market crashes, official recognition by the IMF of the Renminbi as a reserve currency and a significant devaluation while it slowly moves towards a more market-determined exchange rate, as well as many other government interventions and policy easing. In the midst of all these developments, it may be challenging to keep an eye on China’s long-term goals, ambitions and initiatives, most notably, the massive efforts China’s leadership is putting into its ‘going global’ strategy. These efforts are shaped more and more by the so-called ‘Belt and Road’ (B&R) initiative, an initiative that is gaining wider recognition and momentum in public opinion in China, but not necessarily yet outside the country…..
Please click here for the full article.
Editor's picks
Trending articles
Latvia: A Ready Business Platform in the Baltics
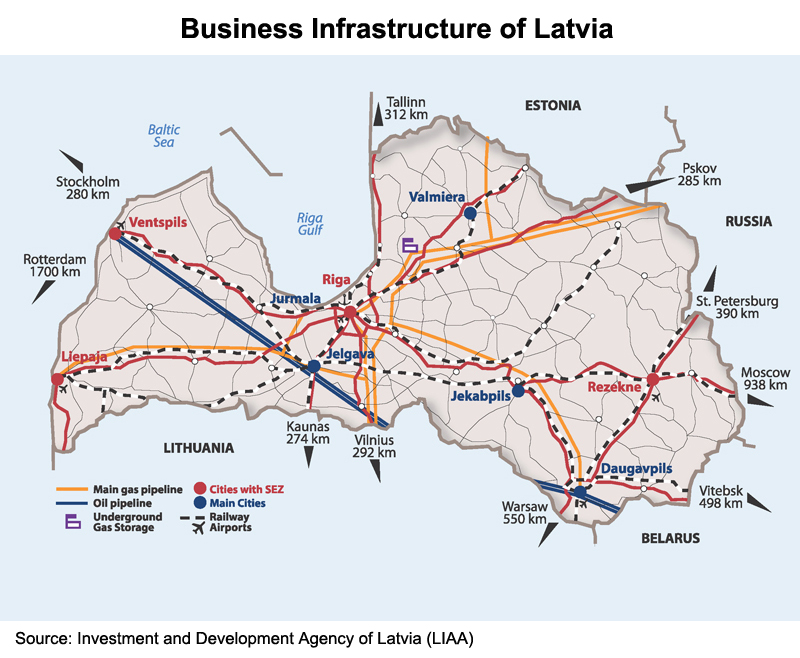
Sandwiched between Lithuania and Estonia, Latvia provides a strategic location in the Baltics for business operations targeting developed economies of the EU as well as the emerging markets to its east. On top of a well-developed rail, road and pipeline infrastructure, Latvia is privileged to also have the busiest airport among the three Baltic States. On the financial front, the mushrooming of Latvian banks in Hong Kong and the ongoing talks regarding a Latvia-Hong Kong comprehensive double taxation agreement (CDTA) further illustrate how Latvia is keen to develop itself into a business platform in the Baltics for Hong Kong and Asian traders and investors. Meanwhile, in tandem with closer economic ties, Hong Kong, with its heightened role as a “super-connector” under the Belt and Road Initiative (BRI), can be a vital hub and springboard for Latvian entrepreneurs such as green tech companies. Latvia can also be a cost-effective and convenient location for high-tech, high-value manufacturing.
Latvia as a Regional Transit Point
Situated on the EU’s eastern border with Russia and Belarus, two million-strong Latvia is one of the main transit points for both north-south and east-west trade flows. It connects not only the EU with the CIS countries and Asia, but also markets further afield such as the Americas. Accounting for 8% of GDP and more than 8% of employment in 2014, the transit and storage sector remains one of the country’s strongest. It is estimated that nearly 90% of the turnover in Latvian ports, more than 80% of Latvia’s rail cargo and a large proportion of its oil and oil products transported via trunk pipeline systems are in transit. Such a pivotal role gives Latvia the region’s busiest airport and several of its leading seaports.
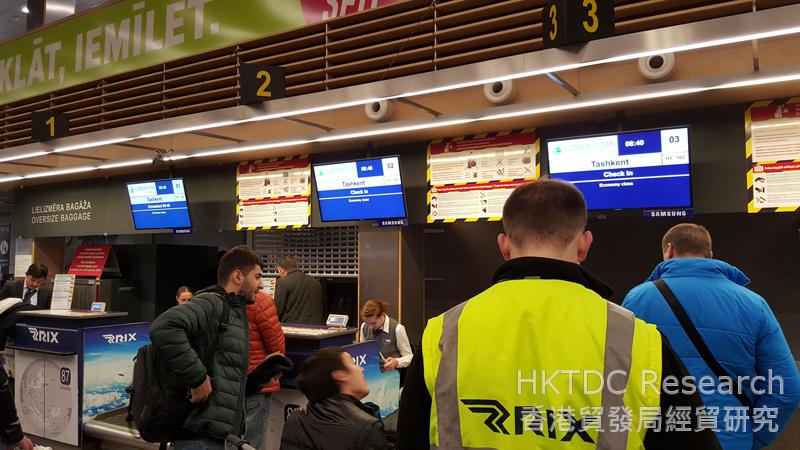
Contributing almost 3% of GDP and supporting 2% of jobs in Latvia, Riga International Airport (RIX) is the regional air hub in the Baltics for both cargo and passengers, connecting to 69 destinations in winter and 89 destinations in summer. With traffic bigger than that of Lithuania and Estonia combined, RIX welcomed a record number of 5,162,675 passengers in 2015, exceeding the 5.1 million passengers registered in 2011. Popular destinations included London, Moscow, Frankfurt, Oslo and Helsinki.
Based at RIX, Latvia’s national airline airBaltic offers easy connections from Riga to over 60 destinations spanning the European Union, Scandinavia, Russia, CIS and the Middle East. Last year, airBaltic opened 14 new routes for the Baltic region – the largest expansion since completing restructuring and achieving profitability in 2013. In addition to a new highlight in Reykjavik, Iceland and the enhancement of the existing network around the Baltic Sea in 2016, direct flights between Riga and Chengdu, China are also in the pipeline, in accordance with the Memorandum of Understanding (MOU) for transport cooperation signed between Latvia and Chengdu municipality in September 2015.
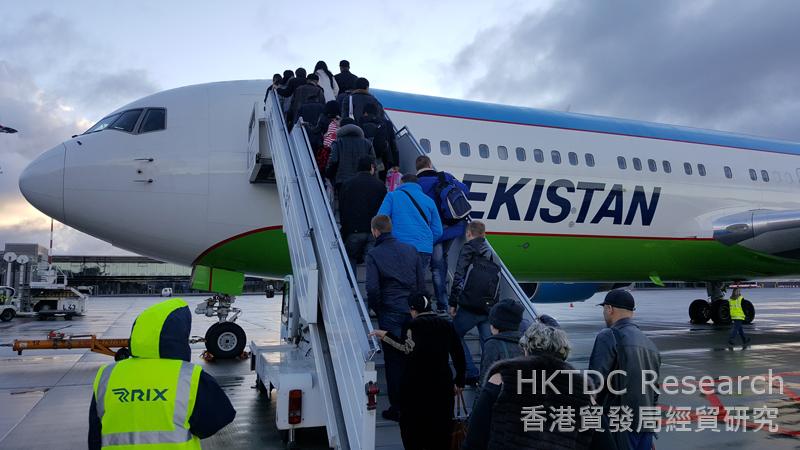
Having a keen eye on Asia for a suitable strategic partner for the national airline, the Latvian government has been in talks with a variety of aircraft manufacturing firms in China, and with two South Korean airlines – Korean Air (KE) and Asiana Airlines (OZ) – over possible cooperation. This accords with the shared development goals of governments in Asia and Latvia in terms of increasing global connectivity.
To this end, Latvia has been paying special attention to its integration with the Trans-European transport network through the development of short sea shipping (such as roll-on/roll-off or “ro-ro” shipping) across the Baltic Sea and multimodal transport infrastructure such as railways and logistics and distribution parks.
Thanks to the former Soviet Union railway-gauge standards, which have been in operation in Latvia for many decades, the country is readily connectible to Asia-Europe rail trade arteries coming to and from Japan and Southeast Asia through the Russian Far East. Such a role will strengthen as the Second Eurasian Land Bridge takes shape and new railway routes better complement existing services. To this end, the growing multimodal freight logistics options between Europe and China facilitated by Kazakhstan Railways and the ongoing “Rail Baltica” project to improve railway connections [1] between Central and Northern Europe, and Germany, give supply chain professionals all the more reason to consider Latvia.
Forming part of the first pan-European transport corridor connecting Finland and the Baltic states to Poland and Western Europe, the Via Baltica (route E67) is the most important transport corridor traversing Latvia in a north-south direction. Given that maintenance funds are collected from excise tax on fuel and vehicle registration fees, all roads, including the Via Baltica, are public and toll-free in Latvia. Along with the financial support from the EU for road improvement, this gives logistics companies another attractive component in their multimodal transport operations.
According to Kreiss International Frigo Transportation, one of the biggest fleet operators in the Scandinavian and Baltic region, Latvia’s logistics cluster is ready to partner with Hong Kong and Asian logistics players to welcome the growing cargo flows expected from the BRI. Running a fleet of more than 1,200 trucks and more than 1 million full truck loads in 2014, Kreiss has extensive experience of bringing in goods from such far-flung markets as Portugal, Spain, Morocco and North Africa and delivering to Scandinavia, Russia and Central and Western Asia.
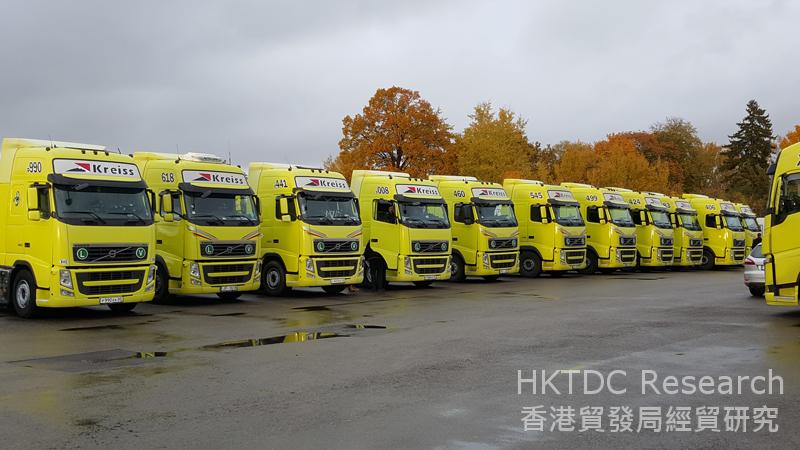
Furthermore, while Latvian trucks cannot drive directly into China, many Latvian forwarding companies have set up branches, affiliated companies or distribution centres in Russia and Kazakhstan to handle cargo coming from the Far East. In the case of Kreiss, some 1,000 trucks can be quickly deployed to connect goods from the Sino-Kazakh border if demand arises. As an authorised cargo transport company for non-military NATO cargo in Afghanistan and a regular freight forwarder for telecommunications equipment heading from Scandinavia to Iran, Kreiss is optimistic about the unblocking of Asia-Europe trade relations brought by the BRI.
Last but not least, the three major ice-free ports – namely Ventspils, Riga (handling mainly coal, forestry products and containerised cargo) and Liepaja (coal, forestry products and metals) – are an important component of Latvia’s multimodal transport infrastructure. Ventspils offers the shortest ferry trip to Sweden in the Baltics (approximately 60km from Stockholm) and ready connection to one of the longest European road routes – the two-track E22, which runs from the UK to Russia and other CIS countries. It also boasts a transshipment hub not only for commodity exports from Russia and CIS countries, such as coal, oil, chemicals, minerals, grains and fertilisers, but also general cargo and regular ro-ro to and from Scandinavia (Nynäshamn, Sweden) and Central Europe (Travemünde, Germany).
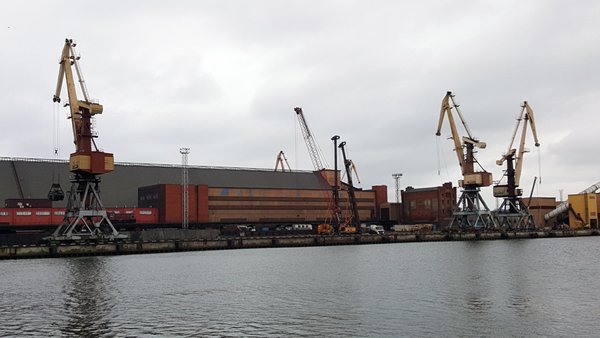
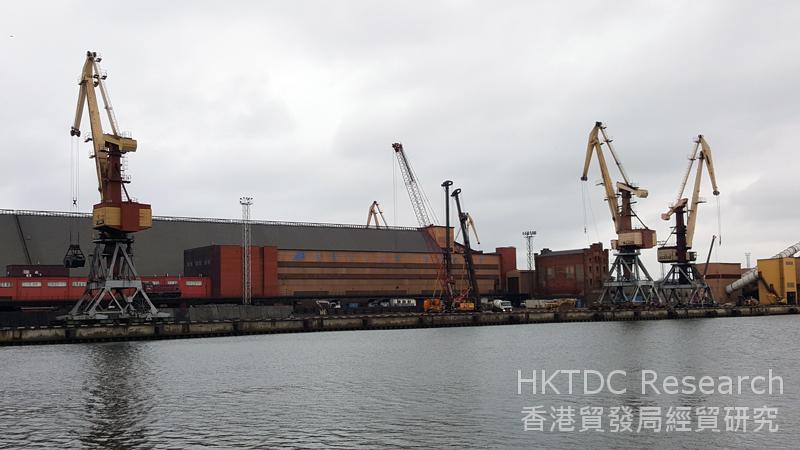
As one of the four special economic zones [2] in Latvia, Ventspils enjoys favourable incentive schemes for new business such as 80% relief on direct taxes (corporate income tax and real estate tax) and significant discounts on VAT and excise tax. It has aroused the interests of a number of Chinese investors to assess the possibilities of setting up a logistics and distribution centre there for better supply chain management and timelier support/after-sales services to both buyers (EU companies buying from China) and suppliers (Chinese companies selling to the EU).
The free-zone status is also attractive to non-EU manufacturers – including those from Asia, Russia and CIS countries – looking to set up plants for local production or assembly. This means they can enjoy “Made in the EU” status and are therefore exempt not only from import tariffs but also anti-dumping and countervailing controversies or even trade sanctions such as those in place between the EU and Russia.
Latvia as a Financial Partner
Despite its small domestic market, Latvia has a diverse economy. With limited natural resources, however, it relies heavily on the services sector. Aside from logistics, finance and green technology are among the bright spots for Hong Kong companies looking for opportunities in the Baltic country.
In the wake of the economic crisis of 2008, Latvia has implemented several pro-business reforms, with a focus on developing itself into an investment destination, including adopting the euro as its currency on 1 January 2014. These measures, together with the 16+1 formula [3] promoting regional co-operation between Central and Eastern Europe and China and the ongoing negotiation of a CDTA with Hong Kong, is set to make business and trade co-operation between Hong Kong and Latvia flourish.
Taking advantage of this growing momentum, several Latvian banks – ABLV and Expobank – have established formal representation in Hong Kong. Their operations in the SAR remain largely related to their Russian and CIS clients’ payments to and from China. However Expobank has chosen Hong Kong for its debut in Asia and is applying for a banking licence to prepare for broader business coverage, including international clients such as traders who need banking services in the Baltics, the CIS and Russia.
Source: ABLV and Expobank
Nowadays, with EU and US banks becoming generally more risk-averse towards Russian clients, Latvia, with 38% of residents claiming Russian as their mother tongue, can provide partners for Hong Kong banks and financial institutions to conduct due diligence investigations such as know your customer (KYC) and anti-money laundering (AML) requirements on Russian and CIS clients.
On the other hand, Latvian companies are small in size and capital. It is estimated that even the top-10 Latvian companies do not have enough capital to list in Hong Kong. With a typical project size of around €5-25 million (HK$43-213 million) Latvia is therefore not very attractive to state-controlled Chinese investors who are looking for big projects such as container terminals, distribution centres, and electronics and F&B (food and beverage) processing facilities. To attract smart money and angel funding, Latvian companies, despite their small size, need to make themselves visible to prospective investors. In this regard, Hong Kong can be an ideal platform for Latvian project owners to look for cooperation opportunities with Asian investors hunting for investment projects of different sizes.
Latvia as a Green Tech Supplier
Recognised as one of the greenest countries in the world, Latvia is active in promoting green technology in everything from recycling technologies to smart grid technologies. Getliņi EKO was created in 1997 to run the largest waste treatment project in the Baltic States – the Getliņi waste landfill (which has been in operation since the beginning of the 1970s) – and turn it into a modern waste management site that generates electricity by collecting methane gas from the decomposing garbage in the landfill. The company has been developing new technologies capable of being deployed elsewhere.
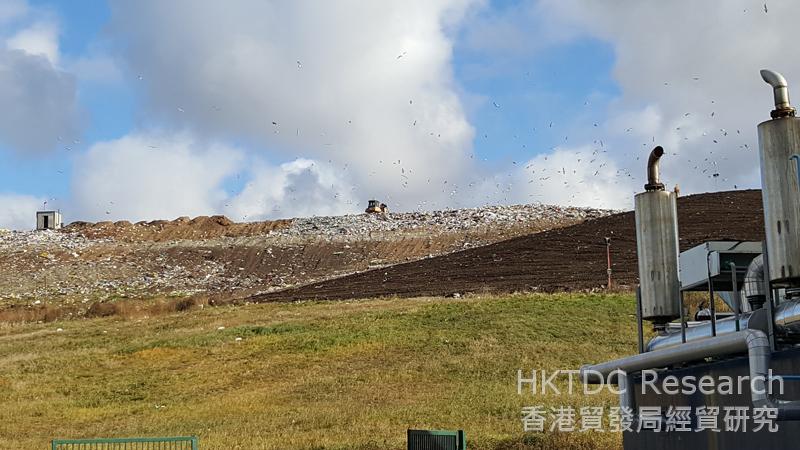
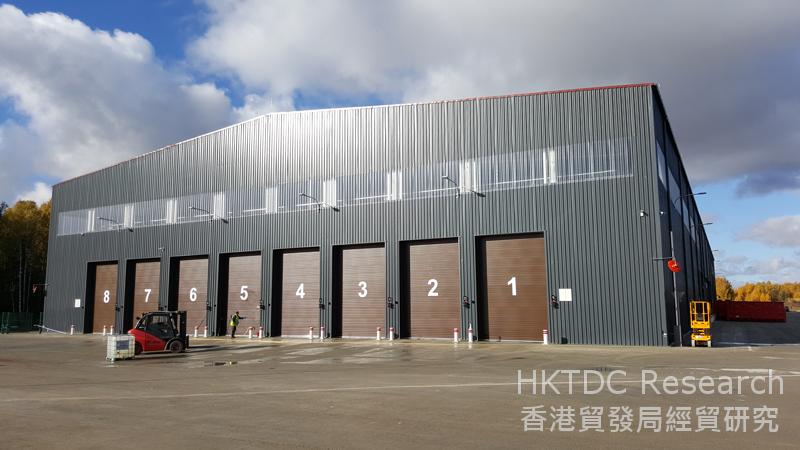
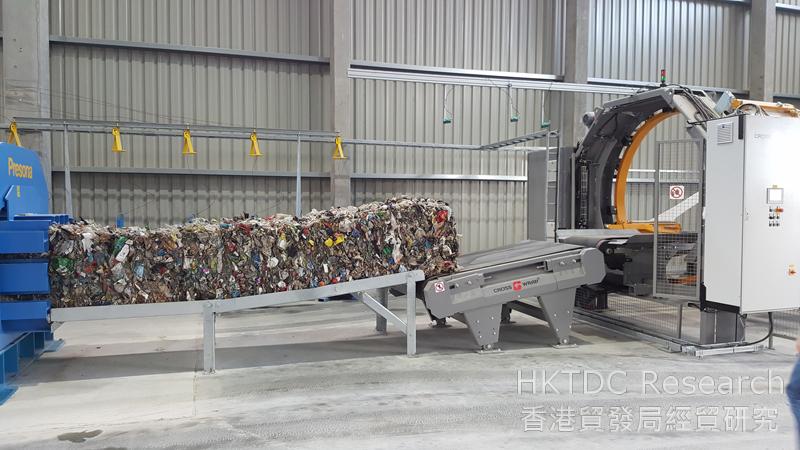
Handling half of the country’s rubbish by accepting solid municipal waste from private and corporate clients every day within the Riga waste management area from 7am till 10pm, Getliņi EKO Ltd is focused on achieving three inter-related goals in the waste management process – reducing air pollution from methane gas, preventing ground water pollution and modernising the Getliņi landfill.
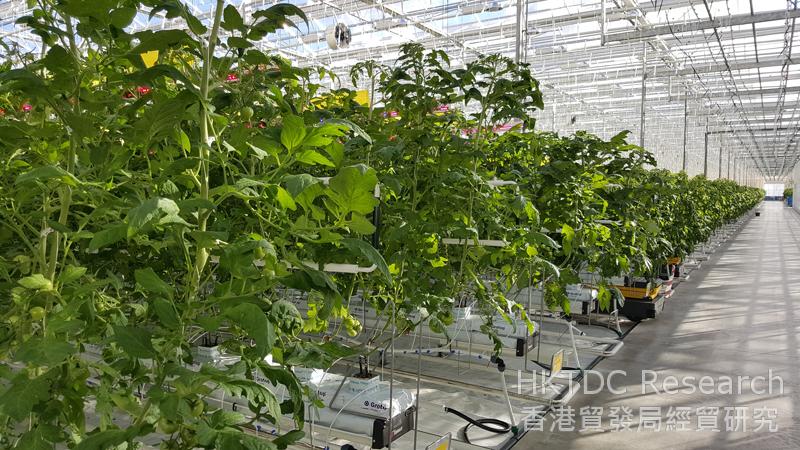
As the first company in Latvia to introduce full utilisation of methane gas from the landfill for production of electricity via internal combustion engines, Getliņi EKO has transformed the Getliņi landfill from being a rat-infested health hazard – once an obstacle to Latvia’s EU membership. Now, more than 450 tonnes of yellow tomatoes are grown with the heat generated from the cooling of the energy generators, with the facility now acting as a model of good practice in waste management for EU policymakers to promote. Following the opening of a recycling factory near the landfill site in October 2015, Getliņi EKO has a new, 10-year goal of reusing up to 90% of the waste deposited in the Getliņi ecological landfill every year and better, earlier sorting of recyclable materials.
With solid waste management becoming an increasing challenge for governments in developing countries amid fast-paced urbanisation, Latvia’s experience offers an example to follow. Indeed, Getliņi EKO is ready to export its business model and provide consultancy services covering everything from the establishment of landfills and the installation of energy generation and ground water purification devices to design, securing financing and ultimately construction and operation.
In all likelihood, Latvia’s green solutions can suit the needs of many BRI countries where solid waste management (including sewage treatment) and heating for agricultural and even industrial purposes are common headaches. In terms of facilitating technology transfer and the development of new applications in new scenarios, especially the Chinese mainland, Hong Kong offers a ready platform for facilitators such as Latvian banks (which have representation in Hong Kong) to approach prospective clients from China and other parts of Asia.
Latvia as a Production Base
Despite the dominance of services, Latvia, given its competitive land and labour costs and tariff-free access to the 500 million-plus consumers living in the EU, can be a cost-effective and convenient location for high-tech, high-value manufacturing. An extension of the Tongyu Group’s facilities in Guangdong, Tongyu Communication is the company’s first manufacturing project overseas, in Riga. There it has built an assembly plant making quality microwave antenna products using key components imported from the group’s factory in Guangdong since 2014.
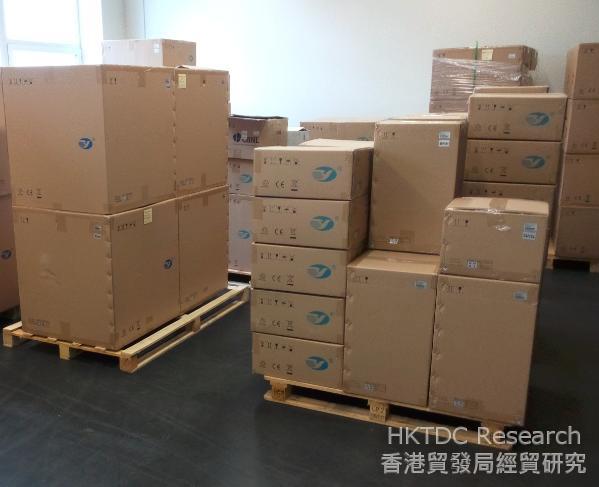
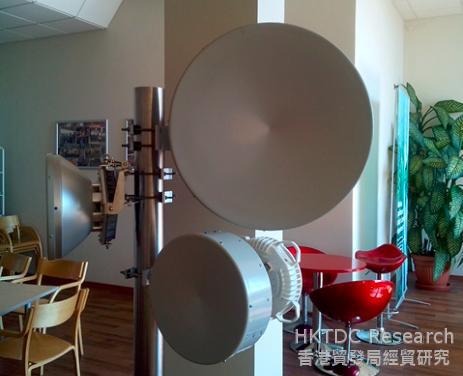
Fully compliant with EU standards, the assembly plant in Riga enables the company to provide European clients with Ex Works Riga (EU) invoicing and extended technical design and R&D services from its headquarters in Guangdong. Technical and logistics support have also become far easier to provide, not just in the EU market, but also to Russia, the CIS and other nearby markets.
Given the rising production costs in the Chinese mainland and the enhanced connectivity promoted under the BRI, more and more manufacturers (including those run by Hong Kong entrepreneurs) on the mainland will likely consider the feasibility of relocating their value-added production closer to final markets such as the EU. This will also help them to stay competitive in terms of response time and after-sale services.
Latvia, thanks to its cost advantages to investors, as well as its competitive tax rates (including incentives for R&D and state credit guarantee to foreign investors), can be considered an attractive option in the EU for firms considering relocating parts of their manufacturing.
[1] This project would serve as the first step in Latvia’s transition to European railway-gauge standards.
[2] There are four special economic zones in Latvia, namely Ventspils, Riga, Liepaja and Rezekne.
[3] In 2011, China revived its cooperation with a group of 16 Central and Eastern European (CEE) countries: Estonia, Latvia, Lithuania, Poland, the Czech Republic, Slovakia, Hungary, Romania, Bulgaria, Slovenia, Croatia, Serbia, Bosnia and Herzegovina, Montenegro, Albania and Macedonia. In 2012, the first meeting at a heads of government level was held in Warsaw, marking the official launch of the “16+1” formula.
| Content provided by |

|
Editor's picks
Trending articles
Seizing the Opportunities Brought About by “One Belt and One Road” and Seeking New Directions for Hong Kong’s Economy (1)
By Martin Liao (Legislative Council Member, Commercial (Second) Functional Constituency)
This year is the year when China starts to build the “One Belt and One Road”, and the steady progress of this strategic initiative is an important part of the “13th Five-Year Plan” that the country is currently focusing on formulating. The HKSAR Government should provide leadership and support to various industries to promptly capture the opportunities arising from the “One Belt and One Road” and seek a new direction for Hong Kong economy’s as a whole.
Provide leadership to industries to promptly capture opportunities
China has started discussions with the countries and regions along the Silk Road Economic Belt and the 21st-century Maritime Silk Road on building a new framework for regional economic co-operation and constantly enriching the contents and approaches of co-operation under the initiative. Hong Kong indeed needs to participate as soon as possible in order to benefit from it. Therefore, following my request for the Chief Executive to obtain information at the government level on the latest developments of the “One Belt and One Road” for Hong Kong’s business community earlier this year, at the beginning of the current legislative year recently, I put forward a motion at the Legislative Council, urging the HKSAR Government to provide leadership and support to the various industries to promptly capture the opportunities arising from the “One Belt and One Road” and seek a new direction for Hong Kong’s economy as a whole.
The motion was eagerly deliberated and adopted by the Legco members. It is evident that despite the diverse political views within the Legislative Council, the vast majority of Legco members agree with the need to capitalize on the “One Belt and One Road” to seek a new direction for Hong Kong’s economy. In fact, because Hong Kong has been slow in economic restructuring over the years, some of its inherent advantages have gradually faded. Coupled this with the external economic uncertainties, Hong Kong is indeed facing both external and internal problems. As the “One Belt and One Road” spans across Asia, Europe and Africa, it will be the world’s longest economic corridor and largest economic engine. With an overall economic value estimated to be as high as HK$163 trillion, its development potential is quite amazing.
China’s “Vision and Actions” on building the “One Belt and One Road” have given rise to a very broad space for industrial development, including transportation, port infrastructure and e-commerce, among which are many industrial areas where Hong Kong has advantages. The problem is that, specifically, where should Hong Kong’s industries start?
Dare to look beyond
The Chief Executive has said that he will first study and then select the industries suitable for participating in the “One Belt and One Road”. I very much agree with this. However, more importantly, I believe that we should set our vision higher and farther, not only to find current opportunities, but more so be bold enough to seek a new direction for Hong Kong’s sustainable economic development over the next five decades or even longer.
First, the industries where Hong Kong traditionally has advantages can capitalize on the “One Belt and One Road” platform to expand into new markets, as well as to upgrade and restructure. For example, in the financial sector, as one of the three major global financial centres, Hong Kong not only has the world’s largest offshore RMB business, but also boasts the largest pool of RMB funds outside of China. In addition, it has a sound financial system, professional financial division of labour, highly transparent and diverse financial products, as well as an excellent financial regulatory system and discipline. It also offers first-class asset management services, bringing together a group of the world’s top financial talents. With these advantages, Hong Kong is fully capable of becoming the premier multichannel financing centre for companies in the countries along the “One Belt and One Road”. According to estimates, just infrastructure construction alone, the “One Belt and One Road” has an investment scale of US$1.04 trillion and transnational investment of about US$52.4 billion. Hong Kong is well-positioned to become a treasury centre of the “Asia Infrastructure Investment Bank” to provide financing for construction projects in the countries along the “One Belt and One Road”.
Strengthening of RMB business hub
In order to meet the huge demand for funds due to the “One Belt and One Road”, China has set up the “Silk Road Fund” and the “Asia Infrastructure Investment Bank”, which also brings huge financing opportunities for Hong Kong, helping to develop its bond market and improve its financial strength. In addition, with the increase in economic and trade exchanges among the countries along the “One Belt and One Road”, the RMB will be used more frequently and financing needs will be more substantial. Plus, with financial reform and opening up, China is striving to build a RMB-dominated regional monetary system in Asia and expand the channels for the RMB to flow back. This is positive for the development of Hong Kong’s RMB market and will strengthen its role as an offshore RMB business hub. The Financial Services Development Council of Hong Kong pointed out that if the RMB is included as a reserve currency, an estimated RMB500 billion to RMB 600 billion will flow out from China, and Hong Kong will be able to play a greater role in RMB capital projects and going global, taking the opportunity to develop into a financial market offering a full range of products and services. Besides, the “One Belt and One Road” spans across many Islamic countries, which could significantly improve the Islamic bond market that has been developing well in Hong Kong in recent years. The development of wealth management, fund management and privately offered funds in Hong Kong will also benefit with the “One Belt and One Road” boosting interoperability among Asian financial markets.
The shipping industry, where Hong Kong still has advantages for the time being, is also likely to scale new heights. As an international shipping hub, a goods distribution centre and a place where logistics enterprises gather, Hong Kong has a world-class international airport and port transportation management facilities, with flight and shipping routes spanning across the globe. Its efficiency in custom clearance for cargo is second to none. Hong Kong can help the regions along the “One Belt and One Road” to replicate inland port cities, and drawing from its experience in rapid custom clearance, it can also help the countries establish cooperation networks to promote cooperation in areas such as joint supervision, data exchange and mutual law enforcement assistance.
Professional support centre for “One Belt and One Road”
Commerce and professional services, which are also Hong Kong’s pillar industries, are likely to improve and form a Professional Support Centre for the “One Belt and One Road” projects. Last year, China surpassed Japan for the first time to become Asia’s largest foreign investor. Hong Kong has always been a platform for Chinese enterprises under the “One Belt and One Road” initiative. According to the Ministry of Commerce, as of end of 2013, the Mainland had made foreign investments of as much as US$370 billion through Hong Kong, accounting for about 57% of its total investment. However, Chinese enterprises are actually still at the initial stage of “going global”, and the “One Belt and One Road” is bound to drive more Mainland enterprises to “go global” and increase their overseas investment and M&A activities. Hence, they will have increasingly stronger demand for Hong Kong’s professional services. Hong Kong is Asia’s leading centre for professional services, and it brings together highend service personnel and professional services. Coupled these with its wealth of international experience, in-depth industry knowledge, rigorous professional conduct and enormous business contact network, Hong Kong can naturally provide the necessary legal, arbitration, mediation, accounting, risk assessment, management and consulting services for the “One Belt and One Road” projects.
This article is firstly published in the magazine CGCC Vision 2015 December issue. Please click here to view the full article.
(Remark: This is a free translation. For the exact meaning of the article, please refer to the Chinese version.)
Editor's picks
Trending articles
Seizing the Opportunities Brought About by “One Belt and One Road” and Seeking New Directions for Hong Kong’s Economy (2)
By Martin Liao (Legislative Council Member, Commercial (Second) Functional Constituency)
The traditional Key Industries in Hong Kong, including the Finance Services, Trading and Marine Services Industry, as I have mentioned in my previous article in this series, surely can benefit a lot from the economic activities arising from the vision of “One Belt and One Road”. For the emerging economic sectors, they can find new directions for development from it as well.
Seize the opportunity to realize the potential of e-commerce
E-commerce is one of the emerging economic sectors that has great potential. It is reported that the scale of the global e-commerce market is expected to reach US$2.3 trillion in 2018, of which the Asia-Pacific region would account for 38% of the market share. And the “One Belt and One Road” is bound to generate more multilateral trade to further “expand the economic pie”. Hong Kong should accelerate the marriage of e-commerce and our traditional advantageous industries to capture these opportunities. The HKSAR Government has already named financial technologies as a new direction for the future development of Hong Kong’s financial industry, and is committed to further enhancing the operational efficiency of the industry and pioneering new development models for new technologies such as payment and settlement systems, big data analysis, cloud computing, information and risk management, and network security. Should the Steering Group on Financial Technologies succeed in its promotion of Hong Kong as a Fintech (financial technologies) hub, a new era of e-commerce would surely come with it. By then, Hong Kong with its advantages in freedom of information technology, convergence of talents, well-established legal system and intellectual property rights (IPR) protections, is absolutely well-positioned to be a Fintech hub for the countries and places along “One Belt and One Road”.
Another emerging economic sector is innovative technologies, which is quite a hot topic in Hong Kong these days. Although the innovative technologies industry in Hong Kong , for various reasons, has failed to play a major role over the years, it has high potential for development as many world-class researchers has been attracted to come and do their researches here. This year, a research team from the City University of Hong Kong, which has developed a specific biological technology for detecting toxins, was awarded the Grand Prix at the Geneva International Exhibition of Inventions. The “One Belt and One Road” is sure to provide a broad platform for Hong Kong’s innovative technology talents to maximize their potential. In this regard, the government too should take advantage of the chance and capitalize on Hong Kong’s well-established legal system and IPR protections to promote intellectual property (IP) trading and smooth its way to become an international IP trading hub.
Well-positioned to be an IP trading hub
“One Belt and One Road” not only can bring new development opportunities to Hong Kong’s creative industries, it can also bring new aspirations to our cultural and creative industries through the cultural exchanges with the various countries and regions far and near lying on the relevant economic corridors. As a matter of fact, creative industries have served as an economic engine for many countries and enhanced their economic strength. By comparison, creative industries in Hong Kong have lagged behind with the percentage share of value added in GDP stood at about 5% at 2013. But according to past records, Hong Kong’s entertainment industry was once dominant in the Southeast Asia market, and the influence of its kung fu movies reached as far as Europe and America, an indication that Hong Kong’s unique culture has full export potential. The HKSAR Government should help to create a favorable environment for Hong Kong’s creative industries to take off again, like assisting the industries to understand the cultures and traditions of the “One Belt and One Road” regions and facilitating various exchanges activities, thereby opening up the market and enhancing Hong Kong’s soft power at the same time.
The fore-mentioned are just a few examples of the numerous opportunities arising from the “One Belt and One Road” vision that I manage to cite in the limited length of this article. Actually it requires the joint efforts of the Government, business community and public to search out all the valuable new economic directions that “One Belt One Road” could render us. The Chief Executive has said that the leading industries of Hong Kong would not be the only ones that can “go global”. I believe our society is expecting the HKSAR Government, after the “13th Five-Year Plan” finalized officially, to keep the public informed of the specifics of the opportunities “One Belt and One Road” can bring to the various sectors in Hong Kong and what support schemes will be provided by the government.
The Government is expected to take the lead
As a matter of fact, if we are to seize all the opportunities arise from the “One Belt and One Road” vision, efforts on the part of the business sector alone is not adequate. Also this is not an efficient way for allocation of resources for society as a whole. In conclusion, the Government needs to play its part in creating a favourable environment in the background, actively participating in negotiating multilateral agreements to facilitate trade and safeguard investment, increasing the number of Asian Economic and Trade Offices, channeling resources and talents to “One Belt and One Road”- related key areas, and effectively helping the business community to capture opportunities. In addition, the Chief Executive has mentioned that he would ponder setting up a dedicated agency to support our country’s “One Belt and One Road” development, and would coordinate with various business associations and professional bodies to participate in the “One Belt and One Road”. These are very good ideas. I hope they can be put into execution soon enough so that the HKSAR Government can start assuming a leadership role and joining hands with the business community to translate the “One Belt and One Road” opportunities into substantive economic benefits.
This article is firstly published in the magazine CGCC Vision 2016 January issue. Please click here to view the full article.
(Remark: This is a free translation. For the exact meaning of the article, please refer to the Chinese version.)
Editor's picks
Trending articles
China-Kazakhstan Border Co-operation in Xinjiang
Xinjiang plans to become a regional transport hub under China’s Belt and Road Initiative. This mainly involves building three transport routes across the autonomous region. The middle route runs across the Central China Plain to Xinjiang through the second Eurasian land bridge and extends to Central Asia and Europe through two ports, one of which is Khorgas.
Located in the Ili Kazakh Autonomous Prefecture of Xinjiang, Khorgas borders Kazakhstan and is 90 km from Yining, 670 km from Urumqi and 378 km from the Kazakh city of Almaty. It is China's closest port to Kazakhstan and Central Asia and the largest highway port in western China. Cargo passing through Khorgas accounted for half of Xinjiang's import/export volume in 2014. The Khorgas Railway has also started operation since December 2012.
In September 2011, the State Council issued Several Opinions on Supporting the Building of the Kashgar and Khorgas Economic Development Zones, which clearly spelled out the relevant supporting policies and established Khorgas' special position in the opening up of Xinjiang, and indeed China, to the outside world. Khorgas was officially established as a city in September 2014 and combines the characteristics of a border area, a customs checkpoint, a commercial city and an international city. It is positioned as a gateway for international trade "linking the east and the west" and a bridgehead for opening up to the west.
A Logistics Hub for Trade with Central Asia
Khorgas, the westernmost port of China, is an important trading port between China and Kazakhstan as well as a node for the opening up of Xinjiang and China as a whole to the Silk Road Economic Belt and other countries and regions. An increase in Chinese exports to Central Asia in the past few years has attracted many logistics service suppliers to set up business in Khorgas. Apart from local firms, there are also logistics companies from other provinces. These serve not just local enterprises in Ili and Xinjiang but also provide transportation, customs clearance and other logistical support to traders and manufacturers outside the northwestern region in their exports to Central Asia. According to reports, the number of companies providing foreign-related warehousing and logistics services in this city has increased from 13 in 2013 to 49 at present. The number of international freight forwarding agents has also increased to 100.
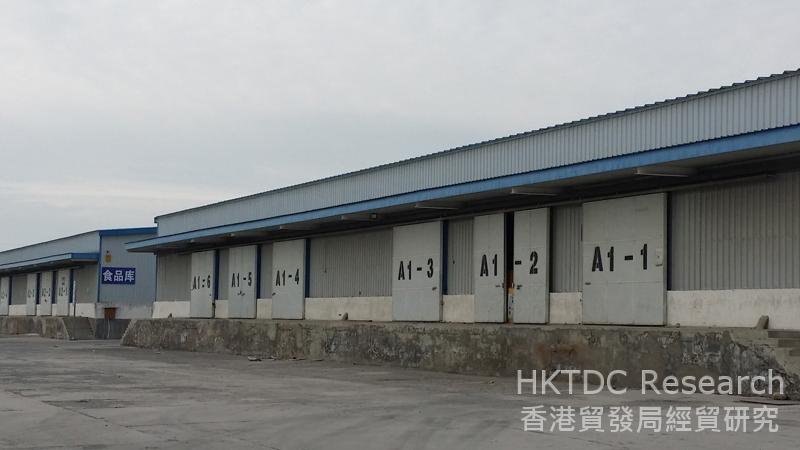
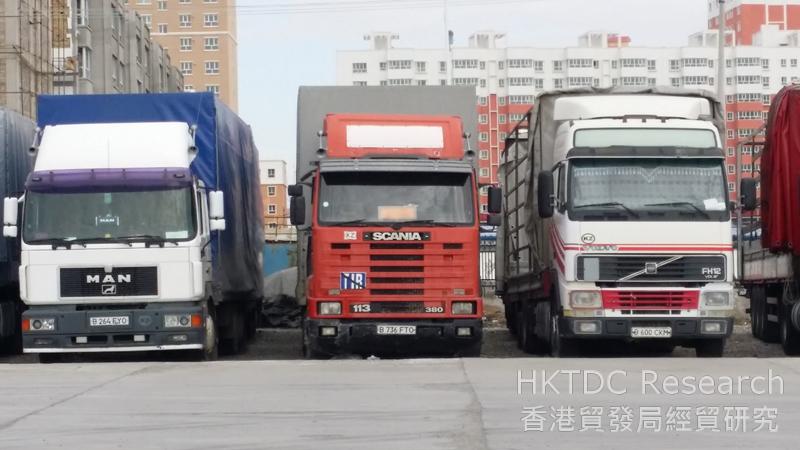
The head of a Khorgas-based warehousing and logistics company told HKTDC Research his business offers a one-stop service in close collaboration with other logistics companies, including customs clearance for Chinese exports and imports from Kazakhstan. Goods from mainland cities are first stored in customs-supervised warehouses and reloaded onto trucks from Kazakhstan after completing customs and quarantine declaration formalities for export as Chinese trucks are only permitted to go 6km beyond the customs checkpoint. Generally speaking it only takes about one day to complete customs clearance on the Chinese side. The goods will be under customs supervision until customs clearance in Almaty, on the Kazakhstan side.
The price of products exported to Central Asia has increased due to improvements in their quality over the past few years, he observed. For example, some exported shoes have an ex-factory price of RMB400 but may retail at over RMB1,000 a pair. Some fur coats from places such as Hebei and Shandong, meanwhile, have a unit price of over RMB6,000. Hong Kong companies interested in venturing into Central Asia may consider using the logistics services available at Khorgas to solve logistics and customs clearance problems when exporting goods to these markets.
The International Border Cooperation Centre: A Frontline for ‘Opening Up’
The China-Kazakhstan Khorgas International Border Cooperation Centre (hereafter referred to as the Centre) is the main focus for implementing the development strategy of building an international trade corridor connecting east and west. As a bridgehead for “opening up” to the west, the Centre – a cross-border economic and trade zone and investment cooperation centre – is a joint project undertaken by China and Kazakhstan. Its aim is to promote economic development in the border areas and reinforce China's economic and trade ties with Central Asian countries such as Kazakhstan.
Located in an area straddling the China-Kazakhstan border, the Centre has a total area of 5.28 km2 and is managed in a closed way. The Chinese section has an area of 3.43 km2, while the Kazakh section has an area of 1.85 km2. It is mainly for trade negotiations, exhibition and sales of products, warehousing and transportation. It has hotels and commercial and financial facilities and hosts all types of economic and trade fairs. With trade liberalisation, goods, people and vehicles may move freely across the border here. General trade, border trade, tourist shopping and other forms of trade exist side by side. Goods entering the Centre are considered as exports, and tax rules for general trade apply to goods entering the Chinese section. Travellers entering the Chinese section of the Centre may bring in duty-free items worth up to RMB8,000 per person per day. The Centre may be viewed as a pilot transnational closed free trade zone.
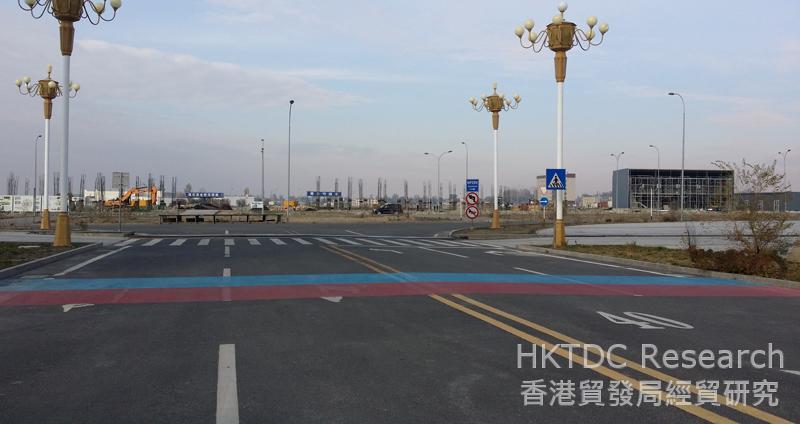
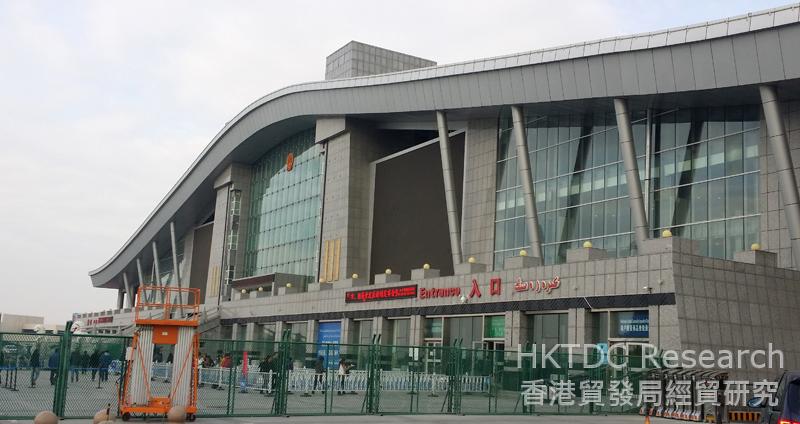
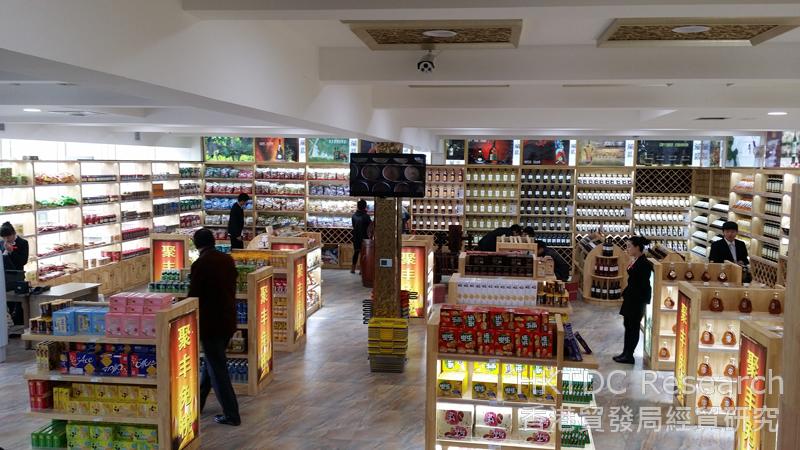
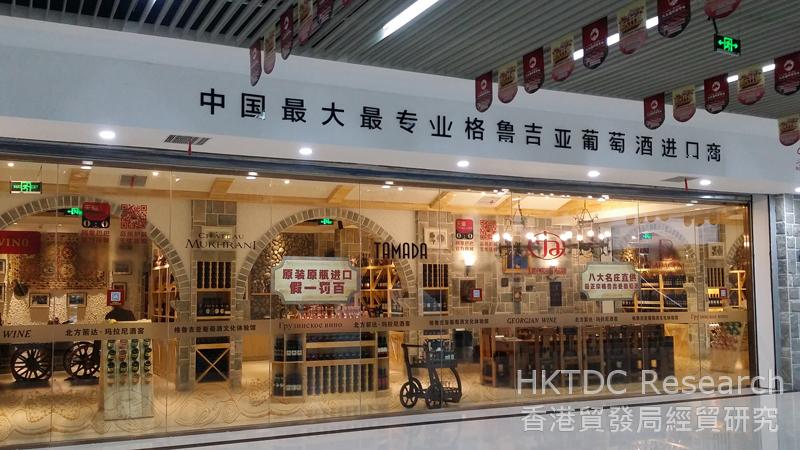
Since the opening of the Centre in April 2012, a number of duty-free shops selling imported goods such as cosmetics, wine from Georgia, chocolate from Kazakhstan, and other goods, have started operations in the Chinese section. Most shoppers are from the mainland. According to Khorgas’ customs statistics, 3.66 million tourists visited the Centre in 2015, up 120% year on year. Commercial projects in the Kazakh section are now under way and are expected to bring Chinese consumers more European products upon completion.
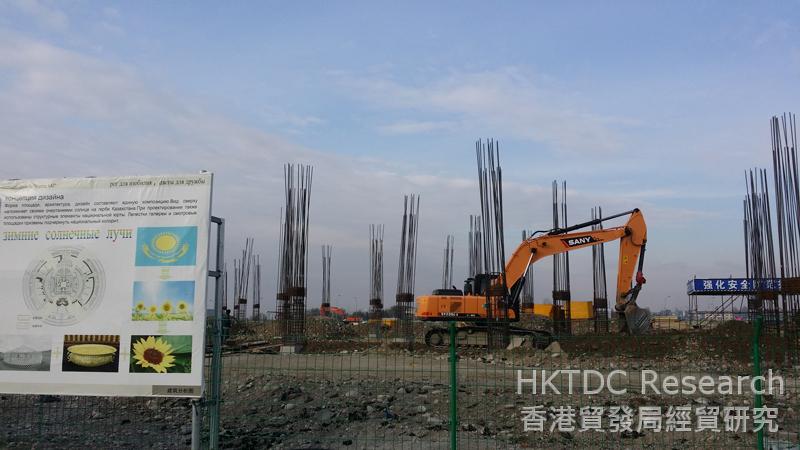
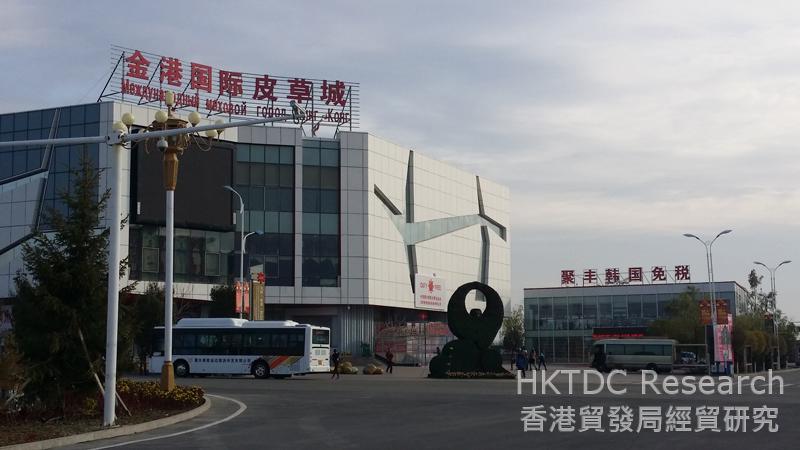
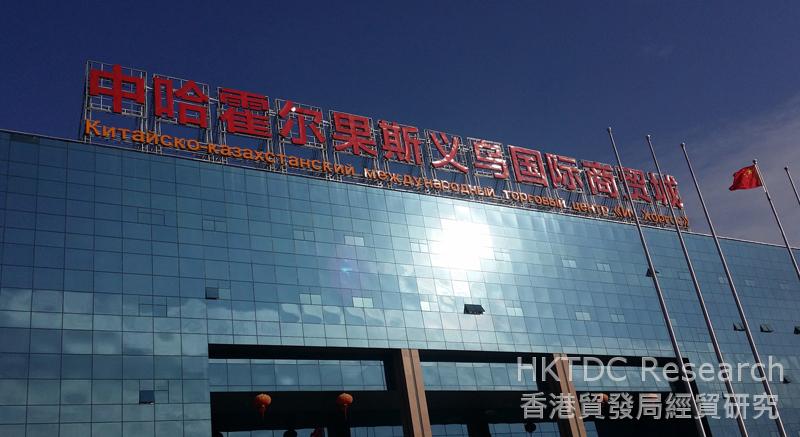
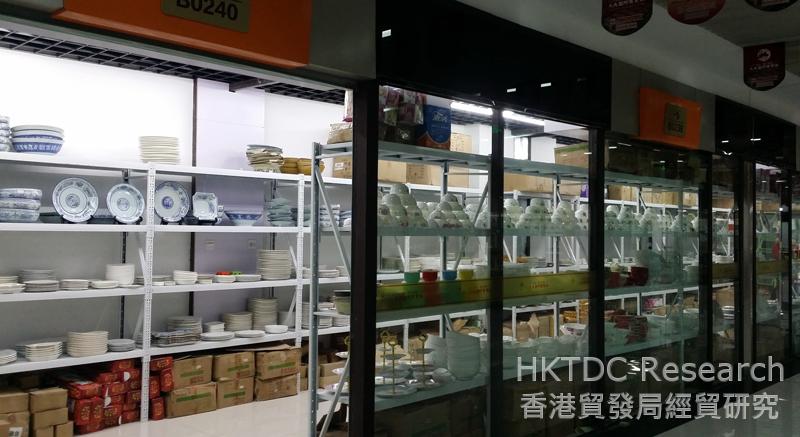
Apart from duty-free shops, a number of business centres have also been completed and opened. They include the Yiwu International Trade City, which is similar to the small commodity cities in Yiwu, Zhejiang province. This business centre is home to many wholesalers and retailers of goods from all parts of the country. It mainly targets Central Asian markets, particularly traders from Kazakhstan, with light industrial goods made in China.
Besides allowing the Centre to function as a free trade area, the State Council also gave the green light to the building of a support zone for the Chinese section 1km south of the Centre. This provides as industrial base for supporting the Centre's development. Its main functions include export processing, bonded logistics, warehousing and transportation. The two are run on the “front shop, back factory” model. Goods entering the support zone from outside are bonded and must be declared to Chinese customs according to general import rules when they leave the zone. Goods entering the zone from other parts of the mainland are treated as exports and are eligible for tax refunds. Transactions between enterprises within the zone are exempt from VAT and consumption tax. The support zone has a planned area of 9.73 km2 and has started operating after passing an acceptance test in September 2015.
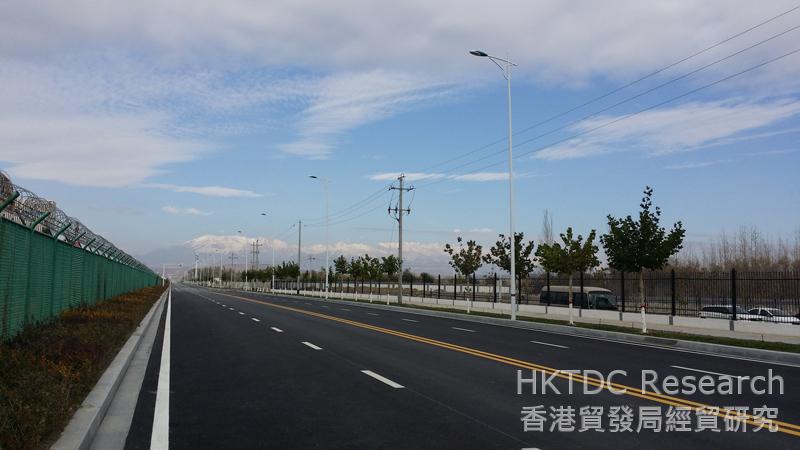
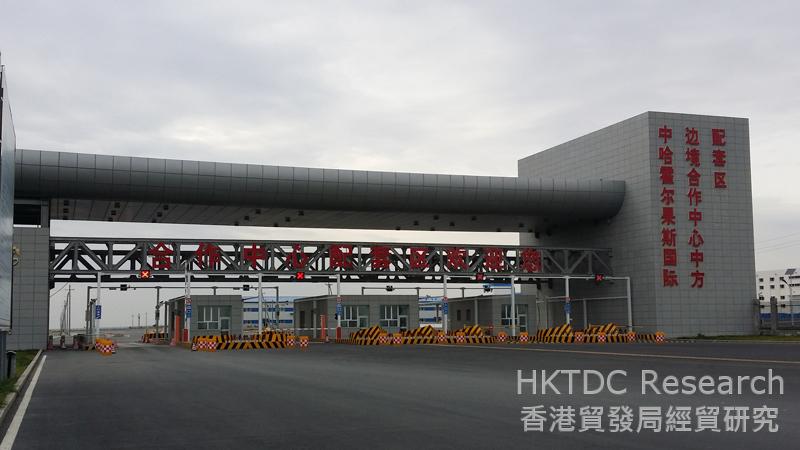
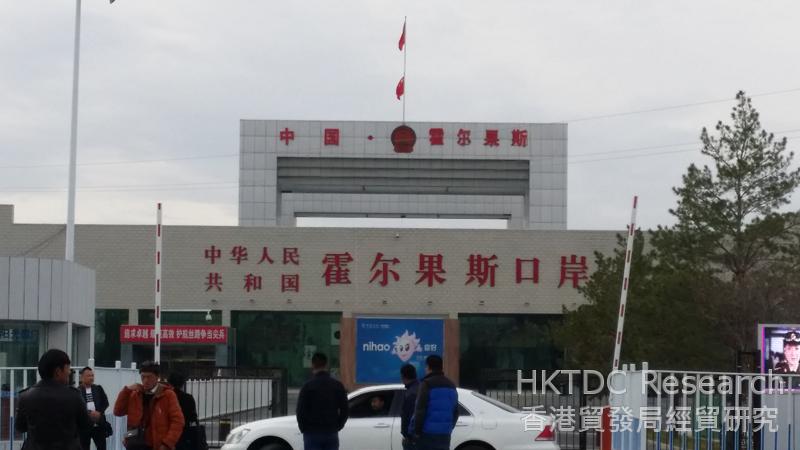
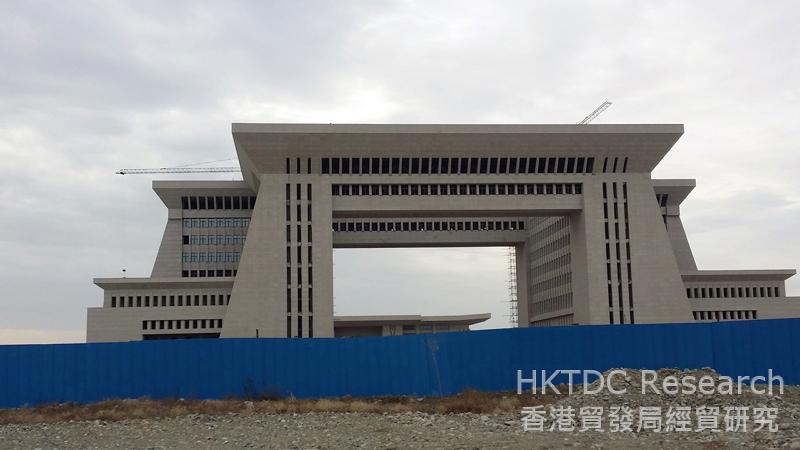
The Centre and its support zone effectively upgrade Khorgas’ trading functions, including foreign trade, product display and sales, warehousing, transportation, tourism and other commercial services. They also provide a key trading centre for China, offering processing, manufacturing, regional sourcing, and transit and transport, for companies to target Central Asian markets. By promoting the export of Chinese goods to Central Asia and the import of goods from Central Asia and even Europe, they merit the attentions of Hong Kong companies interested in tapping business opportunities in Central Asia.
| Content provided by |

|