


Chinese Mainland
Could India Prove to be One of the BRI's Key Development Partners?
Country yet to fully commit, although many commentators see clear benefits stemming from participation.
Given the size and the scope of the Belt and Road Initiative (BRI), India is certain to play an important role in the project, particularly as the proposed Maritime Silk Road (MSR) routes extend into the Indian Ocean. While sharing a long border with China, trading ties between these two major Asian nations have been relatively small, due to both historical and geographical factors, with the mighty Himalayas lying between the two. In addition, the Indian economy, long seen as lagging far behind China's, is finally showing strong growth, making enhanced trade a far more appealing prospect for both parties.
Many now see India as a "sweet spot" at a time when a substantial number of economies throughout the world – including China's – are slowing down. Confirming the country's importance to the BRI project, Ben Simpendorfer, head of Silk Road Associates, a Hong Kong-based consulting firm, said: "India is one of the Silk Road's largest economies and so must play a significant role in the Initiative."
One of the key aims of the BRI is to help China export its excess capacity in a number of sectors, notably steel and cement. Inevitably, this will lead to massive investment in a huge variety of infrastructure projects, including roads, railway lines and seaports.
Dr Srikanth Kondapalli is Professor of Chinese Studies at New Delhi's Jawaharlal Nehru University. He says: "While the BRI is aimed at addressing these excess capacities, it will also bring a tremendous supply of Chinese capital to the neighbouring regions in Asia and beyond."
In many ways, at the heart of the BRI is a complex matrix of infrastructure projects, with many of them likely to have a huge impact on India. With regard to this, two of the most notable projects are the Bangladesh-China-India-Myanmar Economic Corridor (BCIM) and China-Pakistan Economic Corridor (CPEC).
India is, of course, fully aware of the strategic element of the BRI, which some say explains why it has yet to take an official position on the project. There are also a number of sensitivities that will need to be addressed. For one, the BRI is likely to extend into Pakistan, with a number of projects set to be built in Pakistan-controlled Kashmir. India and Pakistan's problematic relationship is likely to cast a long shadow over any project involving the two countries.
In other areas of the BRI, however, India has proved to be a more than willing participant. The country has already signed up to join two of the pan-regional financial institutions likely to be key to the success of the project – the Asian Infrastructure Investment Bank (AIIB) and the New Development Bank. The three banks are likely to be the conduits for the funding for many of the proposed infrastructure projects, said to involve a total spend of some US$8 trillion.
Despite these positive moves, many analysts remain divided as to how the BRI will affect India and its likely impact on the country's relations with its neighbours. The optimists go as far as to believe that, far from exacerbating regional tensions, the Initiative could even lead to stronger economic ties between India and Pakistan.
According to ICRIER, a Delhi-based think-tank, the potential value of the two-way trade between India and Pakistan – should all tariff and non-tariff barriers be removed – is $30 billion, 15 times the current level of trade. Should the BRI and its associated infrastructure developments pave the way for such expansion, it would clearly be to the benefit of all parties concerned.
At the level of individual companies, it is highly like that many of the larger Indian businesses will benefit from their country's participation in the BRI. Such involvement would entitle India's more substantial businesses to bid for a number of the BRI-related projects, although they would face tough competition from companies in Korea, Taiwan and China. Kondapalli, though, is philosophical about the prospects for Indian companies, saying: "Anyone could walk away with a billion dollars' worth of projects."
There are certain areas where Kondapalli's optimism could clearly be vindicated. India is highly competitive in both the software and automotive sectors for instance. In terms of infrastructure, though, it is the Chinese firms that are already involved in many of the relevant construction projects.
Although Chinese companies are already working on projects in the Hyderabad area, it is thought that future developments might be undertaken on more of a joint venture basis between Chinese and Indian companies. This would see the domestic firms focussing on government relations, as well as sourcing local labour and materials.
Simpendorfer believes that such partnerships will characterise many of the future developments, saying: "Indian corporations will inevitably play a critical role when it comes to leading consortiums or partnering with Chinese firms as part of large-scale construction projects."
Tsering Namgyal, Special Correspondent, New Delhi
| Content provided by |

|
Editor's picks
Trending articles
Enhanced Border Trade and New BRI Privileges Set to Boost Guangxi
With the mainland government highlighting the role a number of key border regions will play in the ongoing development of the Belt and Road Initiative, several such regions have been granted special privileges, most notably Guangxi.
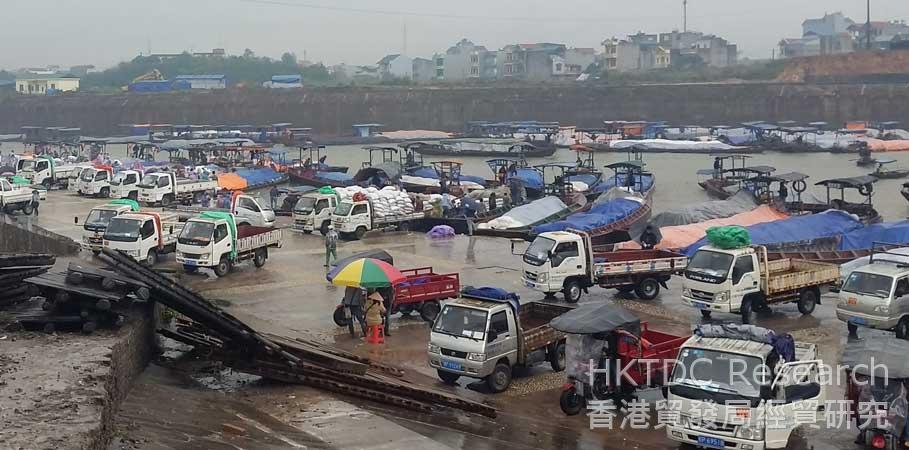
In January this year, the State Council issued its Opinions on Several Policy Measures in Support of the Development and Opening-up of Key Border Regions (Guofa No.72 [2015]). It outlined official support for the development of a number of key border regions, including several pilot zones for development and opening-up, national-level border ports, border cities, border economic co-operation zones, and cross-border economic co-operation zones. The policy specified that these designated regions would all have a leading role in China's Belt and Road Initiative (BRI).
One of these designated areas is Guangxi, an autonomous region in South China bordering Vietnam and one with a long trading history with its neighbour. In order to determine just how Guangxi will benefit from the new policy measures and to get a greater understanding of the potential for small-scale cross-border business in the region, representatives of the HKTDC's Guangzhou Office recently visited two cities – Dongxing and Pingxiang – located along the Vietnam border.
I. Guangxi-Vietnam Border Trade: A Flourishing Sector
In light of Guangxi's advantage in bordering an ASEAN country by land and by sea, the Central Government has designated the region as an important staging post in the development of the BRI. This decision reflects both the region's geographical advantage and its trading history with Vietnam and a number of other ASEAN nations.
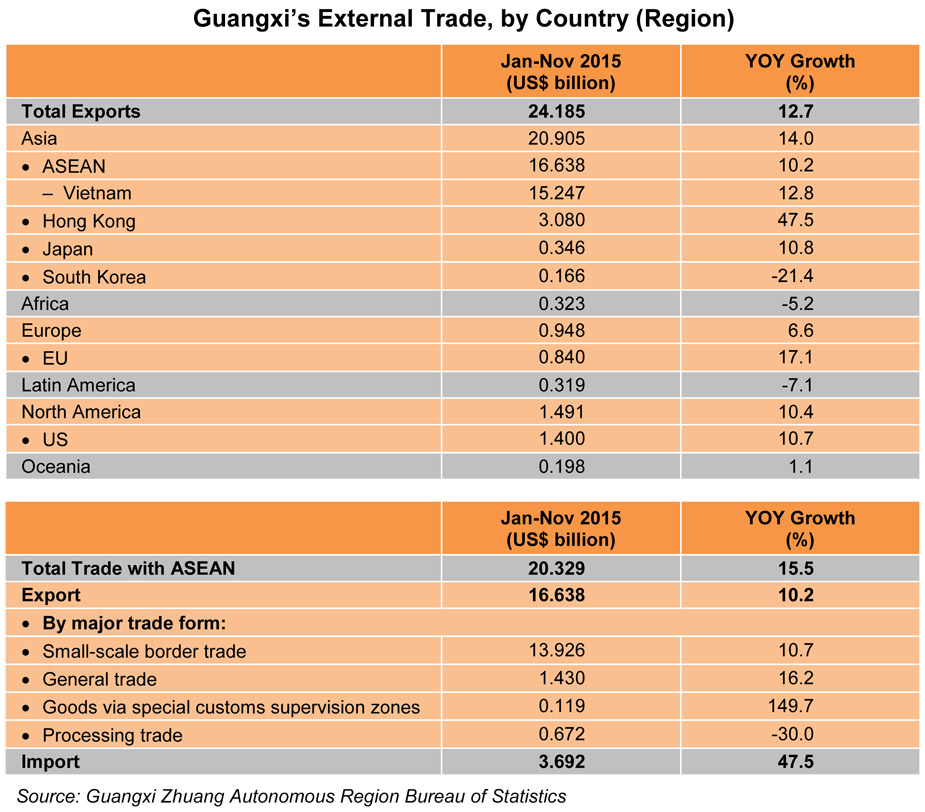
In 2015, according to the Guangxi Statistics Bureau, the total value of trade in the region was Rmb319 billion, an increase of 15% year-on-year. Of this, the total value of small-scale border trade was Rmb106 billion – up 17.1% year-on-year – accounting for 33% of total trade. In terms of trading partners, the value of imports/exports between Guangxi and ASEAN was Rmb181 billion – up 19.6% year-on-year, accounting for over half of total trade. Further afield, the US import/export value was Rmb16.4 billion – up 8.0% – while the EU import/export value was Rmb10.1 billion, up 16.2%.
The term "small-scale border trade" refers to all trading activities (including such things as barter trade and spot trade) between designated enterprises in China and enterprises or other trading entities in the border regions of neighbouring countries, as conducted through land ports specified by the Central Government. These designated enterprises are those businesses granted small-scale border trade rights by border counties or border city districts along China's land border, which have been approved by the Central Government to conduct external trade.
Pingxiang, a county level city in Guangxi, is China's largest border trade port. Dongxing, another major port, lies just 100 metres away from Vietnam's Mong Cai port and is the only Class 1 port in China bordering Vietnam by both land and by sea. A total of 6.15 million border crossings were recorded at the Dongxing port in 2015.
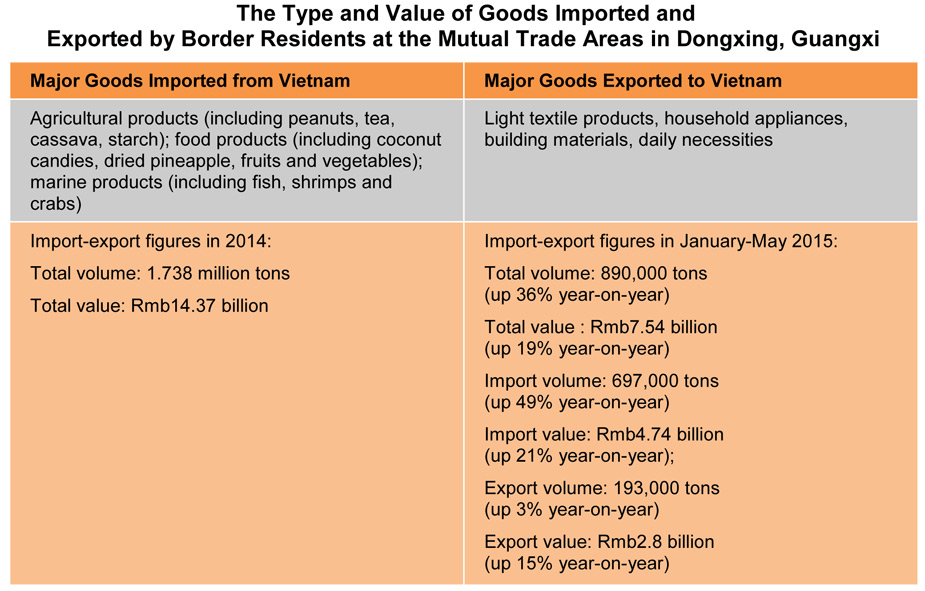
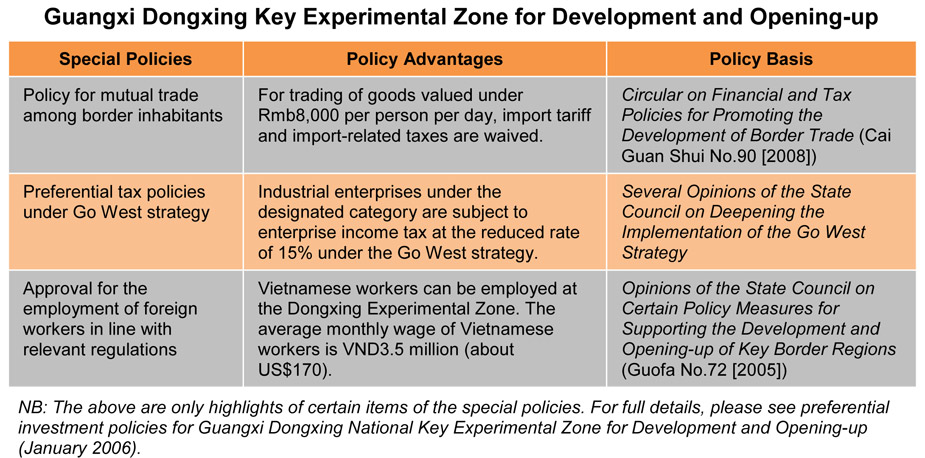
Mutual trade among border inhabitants refers to goods exchanged between border area inhabitants within 20 kilometres of China's land border. Trade can only be conducted at government-approved open zones or designated markets and at a level that does not exceed the prescribed amount or quantity. For daily goods imported by way of mutual trade among border inhabitants (excluding those mutual trade import goods not on the tax exemption list), and with a value of under Rmb8,000 per person per day, import tariffs and import-related taxes are waived. For daily goods exceeding the value of Rmb8,000, import tariffs and import-related taxes will be levied on the portion exceeding the prescribed limit.
II. Special Policies for Key Border Regions in Guangxi
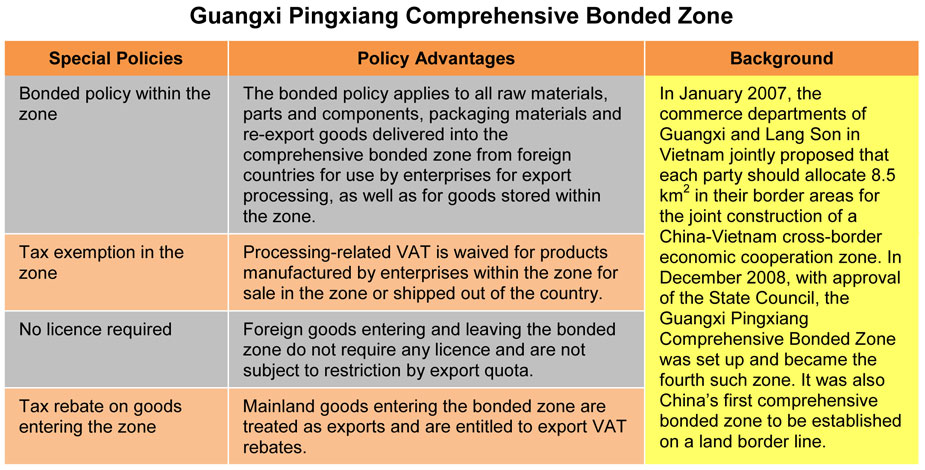
The Central Government divides key border regions into five distinct categories: key experimental zones for development and opening-up; national-level border ports; border cities; border economic co-operation zones; and cross-border economic co-operation zones (for further details, please see Guangxi-Vietnam Border Trade: List of Key Border Regions). Outlined below are the policy advantages of the Dongxing Key Experimental Zone for Development and Opening-up, the Pingxiang Comprehensive Bonded Zone, and the Cross-Border Economic Co-operation Zone (currently under construction in Guangxi).
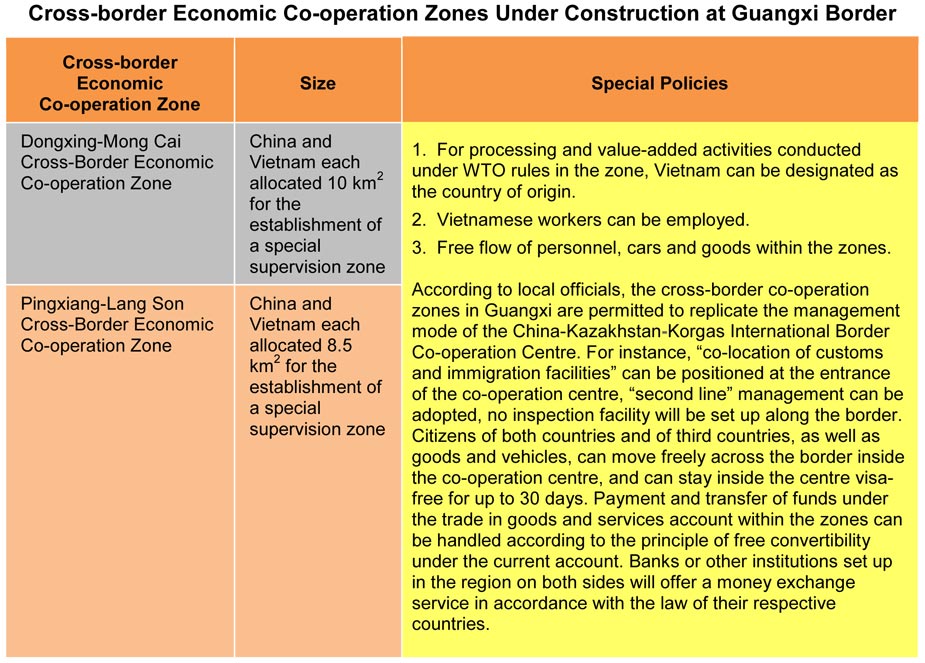
Cross-border economic co-operation zone refers to a special area set up in the vicinity of the border between two countries. The zone is granted special financial, taxation, investment, trade and industrial dispensations. Certain regions within the zone are subject to cross-border special customs supervision. These regions are sub-regional economic co-operation zones entitled to the preferential policies applicable to export processing zones, bonded zones and free trade zones.
In an article published in the People's Daily on 10 December 2015, Gao Hucheng, China's Minister of Commerce, stated that China had already set up 17 border economic co-operation zones in its border regions. In addition to the China-Kazakhstan-Korgas International Border Cooperation Centre, which was established jointly with Kazakhstan, China is currently negotiating with Laos, Vietnam and Mongolia with regard to establishing further cross-border economic co-operation zones.
III. China-Vietnam Small-Scale Border Trade: Big Opportunities
1. Dongxing: Bright Prospects for Cold Chain Logistics
Vietnam produces a vast variety of marine products, with the Dongxing Experimental Zone an important trading port for the import of such items into China. According to official figures, more than 100 containers of marine products are exported from Vietnam into the Dongxing Experimental Zone every day, representing an annual transaction volume of more than 200,000 tons. In 2013, Dongxing exported about 2,355 tons of processed marine products, with an export value in excess of US$11.6 million.
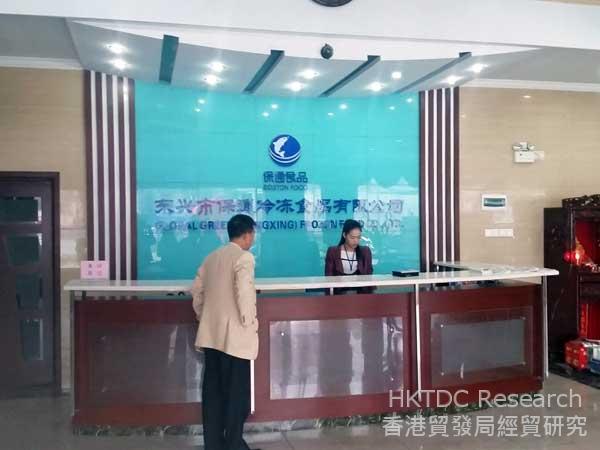
According to Chen Zhenghao, deputy general manager of Global Green (Dongxing) Frozen Food, a company engaged in the processing of marine products in Dongxing, the city has a number of advantages with regards to this sector. Capitalising on the local policy governing mutual trade among border inhabitants, marine products imported from Vietnam are exempt from import tariffs and import-related taxes. Additionally, local companies can employ Vietnamese workers in Dongxing without having to make social insurance payments on their behalf, a considerable saving on labour costs. Finally, with the marine products processing industry in the nearby port city of Zhanjiang approaching saturation point, excess requirements are being passed on to Dongxing and boosting its growth.
Unfortunately, however, Dongxing's cold chain logistics resources are somewhat underdeveloped, with a lack of storage resources and space pushing up the costs of such facilities. According to Chen, the cold storage fee in Dongxing is Rmb7 per ton a day (for cold storage under -18°C), while in Zhanjiang the fee is only Rmb3.5 per ton. Similarly, the wharf loading and unloading fee in Dongxing is Rmb50 per ton and the warehousing management fee is Rmb200 for each use, all of which translates into a higher total cost. In view of this, Chen believes there are now huge business opportunities in the local cold chain logistics industry.
2. Industrial Relocation Spurs New Logistics Routes
The Friendship Gate in Pingxian is China's major land port for exports to ASEAN and has a throughput of more than 700,000 tons of import/export goods and more than 80,000 cross-border vehicles a year. Puzhai, a sub-district of Pingxiang, is home to China's largest fruit market for trade with ASEAN. According to official figures, a total of 1.623 million tons of fruit were imported and exported via Pingxiang in 2014, most of which was transported by road. Every day, more than 600 container trucks pass through Puzhai.
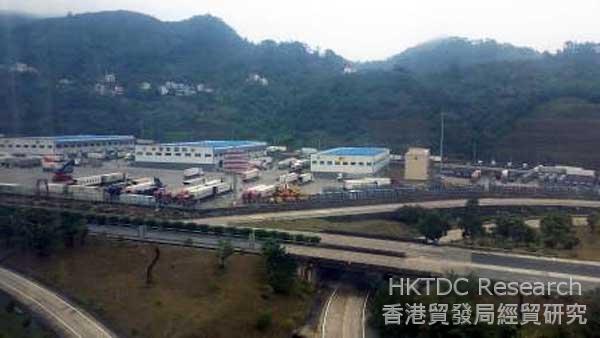
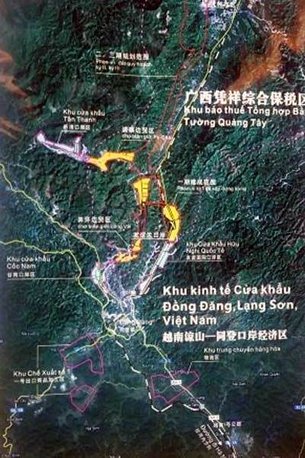
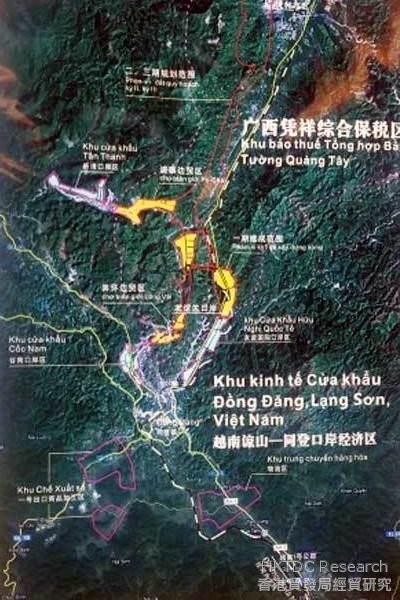
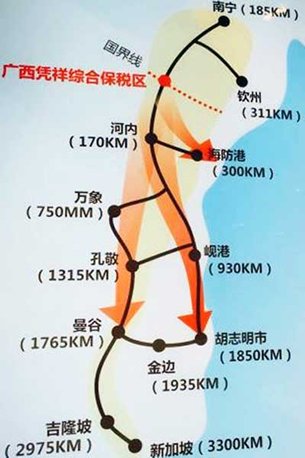
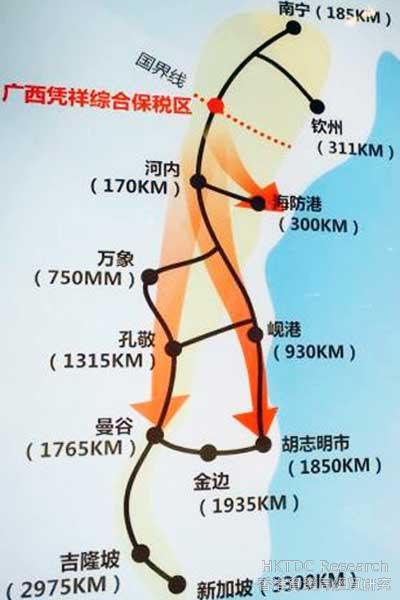
In light of the rising labour and production costs in China over recent years, many multinational corporations – including Samsung, Nokia, LG, Foxconn and Canon – have established factories in areas close to Hanoi, the Vietnamese capital. As a result, a number of ancillary companies also have relocated to the border areas between Guangxi and Vietnam in order to take advantage of the Pingxiang Comprehensive Bonded Zone, which allows them to conduct bonded processing as well as to employ Vietnamese workers as part of a move to lower labour costs. As a consequence, a logistics land route running from Hanoi to Pingxiang, and then on to Hong Kong, has now been established.
According to Li Chuanren, General Manager of Jiedi, a Guangxi-based supply chain company, it currently takes about 14 hours (1,200 kilometres) to travel by road from Hanoi to Hong Kong, with the transportation fee for a 45-foot container being around Rmb30,000. Given the rapid economic development of the Southeast Asian countries and the construction progress of the cross-border economic co-operation zones, local demand for transit warehouses, cold chain logistics, supply chain management and related supporting facilities will inevitably increase.
3. Hong Kong's Tourism Industry and China-Vietnam Cross-border Tour Opportunities
As part of an update to the Closer Economic Partnership Arrangement (CEPA) agreement – signed between the Ministry of Commerce and Hong Kong in November 2015 and due to be implemented as of 1 June 2016 – Guangxi will become the second CEPA pilot region (after Guangdong) in the country.
Guangxi is well-known for its abundance of tourist spots and historical sites. As border trade has become increasingly buoyant in recent years, approval has now been given by both the Chinese and Vietnamese governments for cross-border self-drive tours. According to official figures, Dongxing welcomed a total of 6.711 million tourists in 2015, while the number of tourists received by Mong Cai – the Vietnamese city just across the river – was in excess of one million. During the same year, 22,000 tour groups, representing a total of 150,000 tourists, applied to the Dongxing national border tourism office for entry-exit permits, of which 115,000 were out-of-province tourists.
The new CEPA agreement is widely seen as good news for those Hong Kong service providers looking to access the Guangxi tourism market. Under the agreement, Hong Kong companies in the tourism and hospitality sector can establish a presence in Guangxi and play a key role in integrating the tourist resources of Southeast Asia and the mainland in order to develop new tourist routes and services.
Crystal Ho and Edison Lian, Guangzhou Office
Related article: "State Council Reveals List of Key Border Regions for BRI Development", 26 February 2016.
| Content provided by |
|
Editor's picks
Trending articles
State Council Reveals List of Key Border Regions for BRI Development
The State Council has issued a list of border zones, ports and cities to be accorded special economic privileges in recognition of the major roles they are expected to play in the development of the Belt and Road Initiative (BRI).


I. Key Experimental Zones for Development and Opening-Up (5)
Dongxing (Guangxi), Mohan (Mengla, Yunnan), Ruili (Yunnan), Erenhot (Inner Mongolia), Manzhouli (Inner Mongolia).
II. National-Level Border Ports (72)
Railway ports (11): Pingxiang (Guangxi); Hekou (Yunnan); Korgas, Alashankou (Xinjiang); Erenhot, Manzhouli (Inner Mongolia); Suifenhe (Heilongjiang); Hunchun, Tumen, Ji'an (Jilin); Dandong (Liaoning).
Road ports (61): Dongxing, Aidian, Friendship Gate, Shuikou, Longbang, Pingmeng (Guangxi); Tianbao, Dulong, Hekou, Jingshuihe, Mengkang, Mohan, Daluo, Mengding, Wanding, Ruili, Tengchong (Yunnan); Zhangmu, Jilong, Pulan (Tibet); Khunjerab Pass, Kalasu, Erkeshtam, Torugart, Muzart, Dulata, Korgas, Baketu, Jeminay, Ahitubiek, Hongshanzui, Takeshiken, Ulastai, Laoyemiao (Xinjiang); Mazongshan (Gansu); Ceke, Ganqimaodu, Mandula, Erenhot, Zhuengadabuqi, Aershan, Ebuduge, Arihashate, Manzhouli, Heishantou, Shiwei (Inner Mongolia); Hulin, Mishan, Suifenhe, Dongning (Heilongjiang); Hunchun, Quanhe, Shatuozi, Kaishantun, Sanhe, Nanping, Guchengli, Changbai, Linjiang, Ji'an (Jilin); Dandong (Liaoning).
III. Border Cities (28)
Dongxing, Pingxiang (Guangxi); Jinghong, Mangshi, Ruili (Yunnan); Artux, Yining, Bole, Tacheng, Altay, Hami (Xinjiang); Erenhot, Aershan, Manzhouli, Ergun (Inner Mongolia); Heihe, Tongjiang, Hulin, Mishan, Mulin, Suifenhe (Heilongjiang); Hunchun, Tumen, Longjing, Helong, Linjiang, Ji'an (Jilin); Dandong (Liaoning).
IV. Border Economic Co-operation Zones (17)
Dongxing, Pingxiang (Guangxi); Hekou, Lincang, Wanding, Ruili (Yunnan); Yining, Bole, Tacheng, Jeminay (Xinjiang); Erenhot, Manzhouli (Inner Mongolia); Heihe, Suifenhe (Heilongjiang); Hunchun, Helong (Jilin); Dandong (Liaoning).
V. Cross-Border Economic Co-operation Zone (1)
China-Kazakhstan-Korgas International Border Cooperation Centre
Crystal Ho and Edison Lian, Guangzhou Office
For further information see: "Enhanced Border Trade and New BRI Privileges Set to Boost Guangxi", 26 February 2016.
| Content provided by |
|
Editor's picks
Trending articles
Xinjiang: A Core Component of Belt and Road
The Belt and Road Initiative is China's development strategy for promoting coordination of economic policies, efficient allocation of resources and deep integration of markets among all countries involved. Besides the 60-plus countries along the Belt and Road routes, many Chinese provinces and cities are also actively involved in supporting this initiative. The Vision and Actions on Jointly Building the Silk Road Economic Belt and the 21st-Century Maritime Silk Road (hereafter referred to as Vision and Actions) published by the National Development and Reform Commission in March 2015 also points out that, in advancing the initiative, China will fully leverage the advantages of its various regions. That includes making “good use of Xinjiang's geographical advantages and its role as an important window of westward opening up, making it a key transportation, trade, logistics, culture, science and education centre and a core area on the Silk Road Economic Belt".
Xinjiang's Crucial Geographical Position
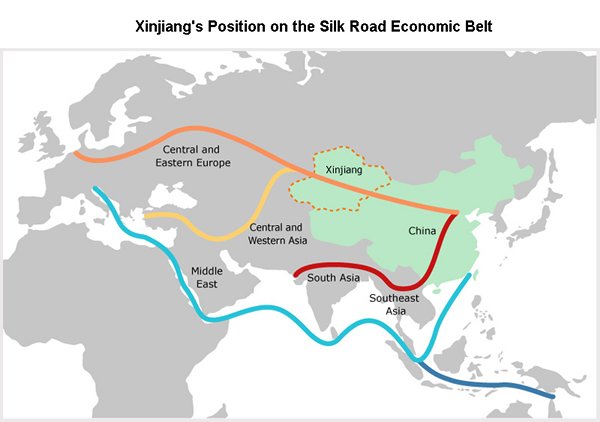
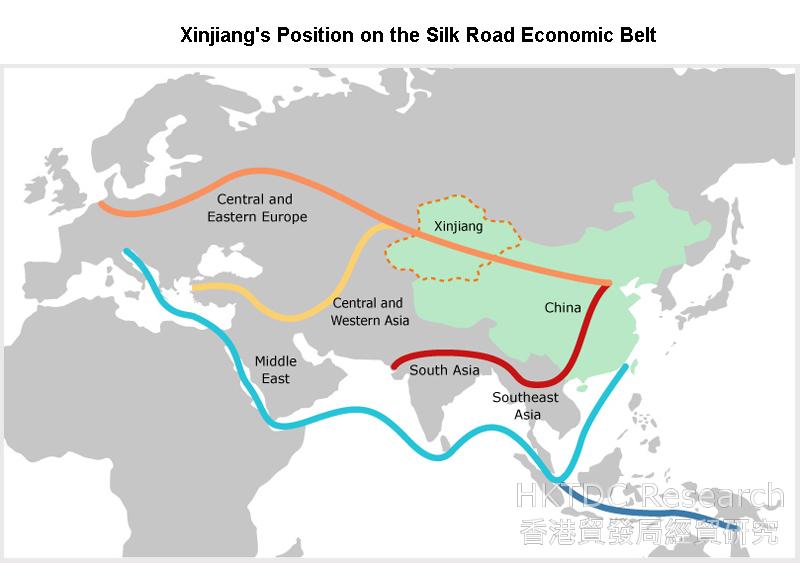
The Silk Road Economic Belt described in Vision and Actions mainly focuses on ways of bringing together China, Central Asia, Russia and the Baltic region of Europe – or, to frame it differently, of linking China with the Persian Gulf and the Mediterranean Sea through Central Asia and West Asia. Either description indicates the importance of Central Asia in the development of the Silk Road Economic Belt, with Xinjiang occupying a crucial geographical position as a land transport link to Central Asia.
Xinjiang is bounded by a number of countries, including Russia, Kazakhstan, Kyrgyzstan, Tajikistan and Mongolia. With its total land frontiers extending 5,600 km in length, its boundaries with neighbouring countries are the longest of any Chinese province. In geographical and transport terms, Xinjiang offers a corridor to many countries along the Belt and Road. It has direct connectivity with neighbouring countries and is the gateway for the exchange of resources, services and more.
Xinjiang Supports the Belt and Road Development Plan
An official from the Xinjiang Development and Reform Commission told HKTDC Research that Xinjiang had started making far-reaching plans in accordance with the Belt and Road Initiative. Although concrete implementation details are still being worked out and examined, a general strategy of developing five centres and three corridors has been adopted.
The five centres refer to a transportation hub, a trade and logistics centre, a financial centre, a culture, science and education centre, and a medical services centre. The last of these will provide medical services to Central Asian countries. According to a Xinjiang official, medical standards in Xinjiang are higher than in Central Asia and over 1,500 people from neighbouring countries received medical treatment in Xinjiang in 2015. As well as Urumqi, hospitals in the border regions also received patients from these countries. The combination of medical services and a tourism offering is a possible area for future development.
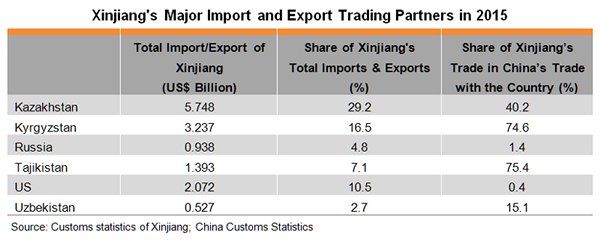
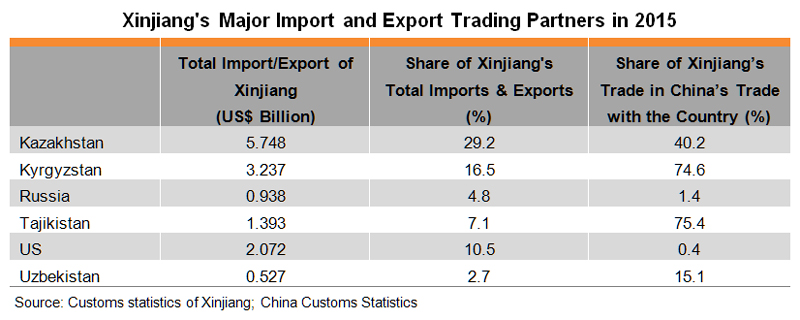
The transportation hub and trade and logistics centre are actually interrelated developments. Xinjiang mainly trades with Central Asia. Xinjiang's total import and export value dropped to US$19.68 billion in 2015 due to falling demand in that region. The fact that import/export trade with Kazakhstan and Kyrgyzstan accounted for 46% of Xinjiang's total trade value and Xinjiang's trade with the Central Asian countries made up a big share of China's trade with these countries indicates that China's trade with Central Asia is mainly conducted through Xinjiang, although many of the export goods originate from coastal and inland provinces.
Aside from trading, Xinjiang also functions as a transportation corridor. Some of the goods imported or exported are not handled by local trading companies but shipped to Central Asia or imported from Central Asia through Xinjiang. According to Xinjiang's customs statistics, the volume of cargoes handled by Xinjiang's ports in recent years increased from 20.93 million tonnes in 2009 to 46.65 million tonnes in 2014, while the total value of imports and exports increased from US$22.29 billion to US$46.14 billion in the same period, exceeding the import and export figures of local trading firms.
Xinjiang to Become A Regional Transportation Hub
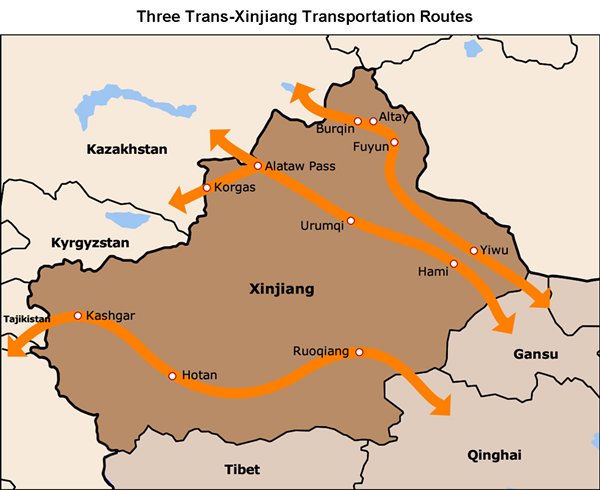
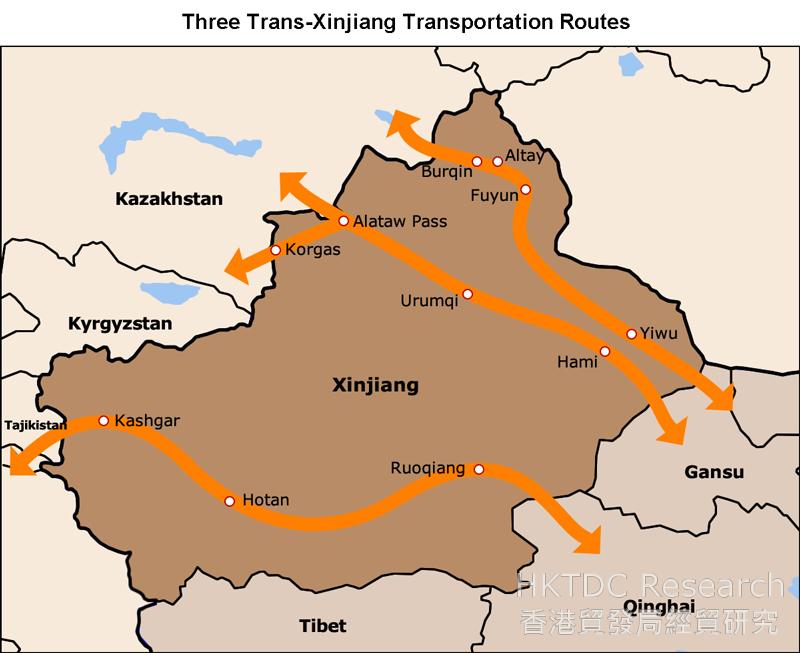
Although Xinjiang faces challenges from weakening demand in its foreign trade in recent years, it still has the geographical advantage of being the corridor for transportation and logistics between the Chinese mainland and Central Asia. For this reason, Xinjiang aspires to become a regional transportation hub under the Belt and Road Initiative. The main priority is to develop three transportation routes across Xinjiang to cities in Central Asia, West Asia, South Asia, Russia and other countries.
The northern route originates from the Bohai Rim. Starting from Beijing-Tianjin-Tanggu, it runs across Shanxi province and Inner Mongolia before reaching Xinjiang, where it runs westwards to Kazakhstan and Russia via Yiwu, Burqin and other counties. The middle route starts from the Yangtze River Delta region and runs across the Central Plain via the second Eurasian land bridge before entering Hami, Turpan and Urumqi in Xinjiang, from where it proceeds to Central Asia and Europe via Alataw Pass and Khorgas respectively. The southern route starts from the Pearl River Delta region and runs across Hunan, Chongqing, Sichuan and Qinghai before entering Xinjiang, where it leads to Tajikistan via Ruoqiang, Hotan and Kashgar and extends southwards to the Indian Ocean coast. According to the Xinjiang Development and Reform Commission, the middle route is already open to traffic and is undergoing further upgrades. As for the other routes, the portions in Xinjiang are expected to be opened to traffic during the 13th Five-Year Plan period (2016-2020).
An Entrepôt and Distribution Centre
Relying on its transportation links, Xinjiang aspires to become an entrepôt and distribution centre for goods flowing between Central Asia and the Chinese mainland. In particular, smaller cargoes can be consolidated here and loaded on containers. The railway container centre now under construction in Urumqi is a major project and it is hoped it will speed up the integration of China-Europe train services, build the city into a westbound container shipping centre and spur the building of logistics parks in neighbouring areas. Xinjiang is striving to open more freight train services and reshuffle train schedules in order to enhance its function as a distribution centre. It will also build national highway transport hubs and more than 30 logistics parks in Urumqi, Yining and other cities in the next five years.
Yining also plans to renovate and expand the existing terminal at its airport during the 13th Five-Year Plan period. It will open an international immigration checkpoint at the airport, establish international air routes to Kazakhstan and other Central Asian cities, begin freight transport targeting Central Asia and build an international logistics centre. At this stage, whether the entrepôt and distribution centre project will materialise depends on whether there is a steady supply of cargoes. According to the Xinjiang Development and Reform Commission, Xinjiang will have to rely on its integrated bonded areas, free trade areas, railways and air transport and also strengthen its function as a distribution centre to attract high cargo volumes.
International Logistics Potential Merits Attention
Xinjiang's development as a transport logistics and distribution centre linking the Chinese mainland and Central Asia, even Europe, is worthy of note. From the perspective of international logistics, infrastructure developments will likely change the present reliance on maritime transport for shipments to Europe. Xinjiang's unique geographical advantage as a buffer between China and Central Asia/Europe and the fact that its ethnic minorities have close cultural ties with people in Central Asia will only enhance its prospects in this area.
Overland transport between Central Asia and Europe has started to develop in the last two years. When cargo volumes increase, demand for transshipment, consolidation and distribution will also increase, thus allowing Xinjiang to further strengthen its hand by providing such services. Providing a gateway for the export of goods to Central Asia and Europe will increase the demand for relevant logistics services, while enhancing its function as a consolidation and distribution centre will also stimulate demand for service management systems in Xinjiang. Moreover, with the development of cross-border e-commerce, it will also have a chance to become a warehousing and distribution centre for coastal manufacturers supplying goods for Central Asia’s e-commerce markets.
Local Processing Industry To Serve Central Asian Markets
In addition to handling goods manufactured in the coastal and inland provinces, Xinjiang also plans to encourage the development of local processing. Besides serving as a base for the production, processing and storage of oil and gas, as a base for the coal power and coal chemistry industry, and as a base for wind power, Xinjiang plans to develop processing industries, with local resources or semi-finished materials made elsewhere being used to produce goods for markets in Central Asia. Resources such as timber, cotton and corn from Central Asia might also be used to produce timber, furniture and other products for re-export to Central Asia or other parts of China.
According to the authorities concerned, the automobile equipment industry is a key one for the Urumqi Economic and Technological Development Zone. Mainland manufacturers have set up business there mainly due to its proximity to Central Asian markets. Export convenience was cited as a key consideration in deciding to set up in Xinjiang by one Guangdong motorcycle plant. Increased transport links between Xinjiang and the central and coastal cities have greatly improved its logistics and connectedness with other regions, making it possible for processing industry manufacturers in Xinjiang to obtain materials and other support from other regions at a lower cost.
To encourage the use of local cotton resources, Xinjiang has introduced policies to support the development of textile and garment industries in recent years. Besides building textile and garment bases in Aksu and Korla in southern Xinjiang and Shihezi in northern Xinjiang, it has also supported the development of printing and dyeing. A special fund for the development of textile and garment industries has been set up to subsidise transportation expenses, staff training, social insurance payments and sewage treatment. In view of the relative weakness of the local supporting industries, Xinjiang plans to develop textile sectors with a short industry chain, such as knitting, carpet-making and home textiles.
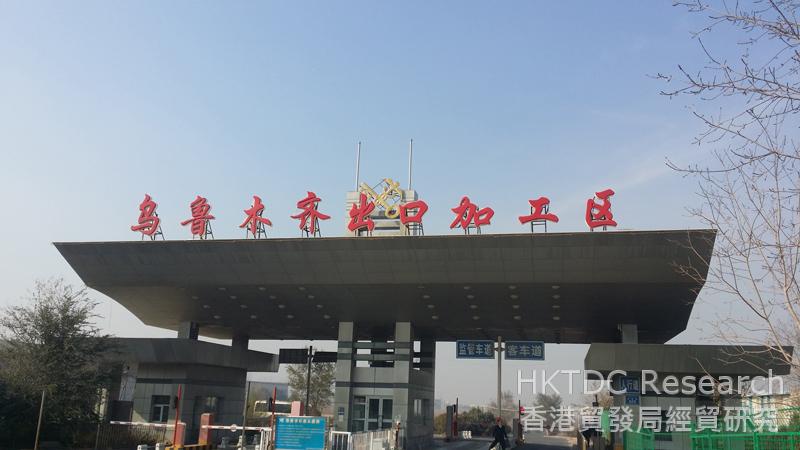
|
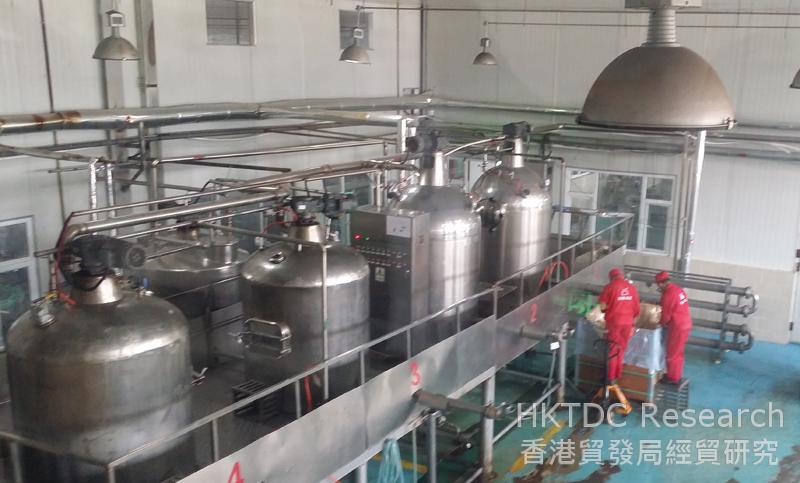
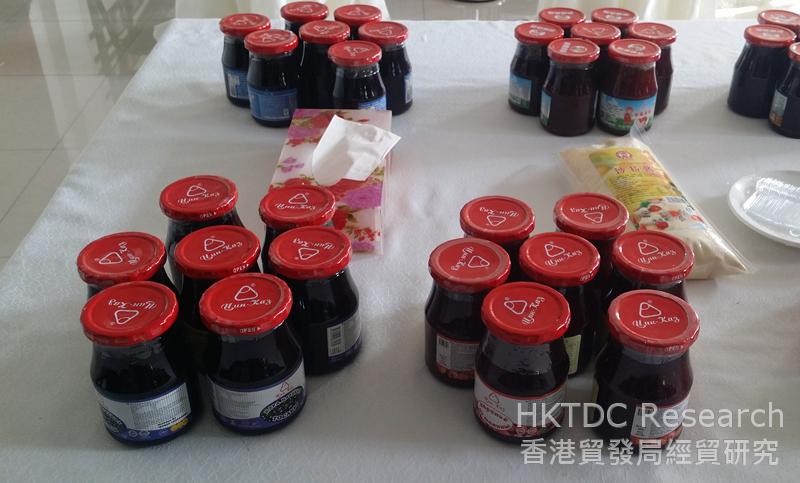
Food processing company Tsinfood chose to set up a factory in the Urumqi Export Processing Zone to produce tomato sauce, fruit jam, canned vegetables, seasoning and other products. Locally grown fresh tomatoes are used to produce tomato sauce. Besides having its own plantations, Tsinfood also outsources to local farmers to produce the ingredients needed. Tsinfood mainly exports its products to Kazakhstan. It has established an R&D base to develop products catering to people in Central Asia. For example, Kazakh consumers have a sweet tooth. Because of the relatively backward manufacturing techniques in Kazakhstan, Tsinfood's recyclable jam bottles are welcomed by local consumers. Today Tsinfood products have a market share of 25-30% in Kazakhstan. The company has even found its way to Uzbekistan and Russia through Kazakh agents.
Tsinfood also has a factory in Almaty, Kazakhstan. The two factories produce similar products. The raw materials (such as tomato sauce) and other supplies needed in the Kazakh plant are shipped from Xinjiang. The company in Almaty is mainly responsible for receiving orders. Although most of the products made at this tomato processing plant are for export, it has begun to sell some of its products to the mainland market in recent years.
|
According to local authorities, land costs and electricity tariffs are relatively low in Xinjiang. Despite the availability of workers locally, training is needed, while wage levels are not significantly lower than in other mainland cities. The Urumqi Economic Development Zone admitted there is a shortage of skilled labour but said it was cooperating with local vocational and technical colleges to train the necessary personnel. It is understood that ordinary workers are paid about RMB3,000 a month.
Some development zones are offering preferential policies. For example, the Yining Industrial Park of the Khorgas Economic Development Zone, kick-started in 2013, is currently focusing on infrastructure construction. It aims to become a regional commercial logistics centre, develop processing industries and export the products to Central Asia. According to the authorities, if enterprises setting up business in the park are engaged in industries prioritised by the state, they are eligible for exemption on enterprise income tax in their first five years and for exemption on the local retention portion of it for a further five years. Tariffs are waived for the import of equipment that is not produced in China. Discount interest loans are available for fixed assets/working capital and subsidies are offered for staff training (especially for the labour-intensive textile and garment industries). The approved land price is RMB150,000/mu.
The State Council issued its Opinions on Several Policy Measures in Support of the Development and Opening-up of Key Border Regions in January 2016. The document called for efforts to promote dominant industries with regional characteristics in the border areas. It also supported giving priority to projects for the processing, transformation and utilisation of imported energy resources and resources in key border areas in an effort to develop outward-oriented industry clusters in these areas. Moreover, the document proposed setting up a special fund for the development of industries in key border areas. These policies show the importance given by the central and local governments to the promotion of industrial development in the border areas. Xinjiang may not be the most suitable destination for the relocation of most processing industries because of its geographical location and other factors. However, for processing industries that make use of local resources and ones imported from Central Asia, and enterprises targeting the Central Asian and South Asian markets, Xinjiang merits consideration, particularly in light of Belt and Road Initiative developments.
| Content provided by |

|
Editor's picks
Trending articles
‘One Belt, One Road’ - An Opportunity for the EU’s Security Strategy
by Jikkie Verlare & Frans Paul van der Putten (Clingendael Institute)
China’s initiative for a modern-day silk road, known as ‘One Belt, One Road’ (OBOR), aims to connect Asia, Africa, Europe and their near seas. Under the definition contained in Xi Jinping’s New Security Concept stating that ‘development equals security’, OBOR can be conceptualized as the most ambitious infrastructure-based security initiative in the world today. This has major implications for geopolitical relations and stability in various regions. It would be beneficial for the European Union (EU) member states to invest in a common response to OBOR, as opposed to engaging with this initiative primarily at the national level. This Clingendael Policy Brief explores how the EU’s existing policy tools and frameworks might be used for enhanced Sino–European security co-operation in relation to OBOR. It is argued that if the European Union works with China under the framework of the EU–China strategic partnership, to align with, inter alia, the planned restructuring of its European Neighbourhood Policy, as well as projects included under its European Maritime Security Strategy and Partnership Instrument to link with the so-called ‘Belt’ and ‘Road’ projects, this would entail true added value for the EU. These steps should be part of the EU’s new Global Strategy for Foreign Policy and Security, which is due to be published in June 2016. This would go beyond the tendency of EU member states to compete for the benefits of increased Chinese investments on their own territories, but instead embed China’s initiative in the common European strategic goal of gaining a larger security footprint in neighbouring regions…
Please click here for the full article.
Editor's picks
Trending articles
A New Opportunity in EU–China Security Ties: The One Belt One Road Initiative
by Jikkie Verlare (Clingendael Institute)
China’s Silk Road Economic Belt and 21st-Century Maritime Silk Road initiative aims to connect Asia, Africa, Europe, and their near seas. The purpose of this study is to examine whether it would be beneficial for the European member states to invest in a common response strategy to the One Belt One Road, as opposed to engaging this initiative primarily at the national level. After exploring how the EU’s deteriorating security environment has caused member states to attach more importance to maintaining the EU’s defence and power projection capabilities, the paper turns to the strategies currently employed to gain more influence over security matters in East Asia. Upon examination, it is shown that three out of four approaches hold little promise of progress. (1) Engagement with ASEAN will only reach its full potential when its integration process is completed, (2) expanding consultations with the US might lead to the perception of a ‘dependent’ Europe and loss of neutrality, and (3) a lack of hard power means that the EU is often not taken seriously as a security actor when participating in regional forums. The remainder of the paper explores the opportunity that has surfaced with regards to the fourth approach: utilising the EU’s strategic partnerships in Asia. Under the definition contained in Xi Jinping’s New Security Concept stating that ‘development equals security’, China’s One Belt One Road initiative can be conceptualized as both the most ambitious infrastructure and security initiative today. It is argued that if Europe works with China in the framework of their strategic partnership to align, among others, the planned restructuring of its European Neighbourhood Strategy, as well as projects included under its European Maritime Security Strategy and Partnership Instrument to link in with the Belt and Road projects, this would entail a true added value for the EU. Doing so will enable members states to not just compete for the benefits of increased Chinese investments on their own territories, but embed China’s initiative in their own strategic goal of gaining a larger security footprint in the Asian region…
Please click here for the full article.
Editor's picks
Trending articles
One belt one road - China's new outbound trade initiative
By Carolyn Dong & Simin YU (DLA Piper)
China’s 'One belt one road' initiative was first introduced by President Xi Jinping during his visits to Central and Southeast Asia in September and October 2013. With the dawn of 2016, it is appropriate time to take stock and review what has been done so far in implementing the initiative, and its future direction.
Set out below is an overview of the One Belt One Road (shortened to OBOR) initiative. As detailed further below, with the initiative successfully launched, key funding institutions established, a regulatory framework deployed and eager diplomats entering into multiple bilateral agreements across the globe, 2016 is now likely to see a rapid acceleration in the uptake of OBOR projects. The potential now exists for powerful partnerships to be established between international and Chinese enterprises to leverage off this initiative.
'One belt, one road' in a nutshell'
'One belt, one road' is a development strategy and framework, proposed by the highest levels of PRC Government that focuses on connectivity and co-operation among countries along two main routes, the land-based 'Silk road economic belt' and oceangoing 'Maritime silk road' which run through the continents of Asia, Europe and Africa, connecting vibrant East Asian economies at one end and developed Western European economies at the other, while encompassing more than 65 countries along the route. The OBOR initiative covers countries as diverse as Singapore, Georgia, Kenya and the Netherlands.
The strategy underlines China's push to take a bigger role in global affairs, and its need to export China's production capacity in areas of overproduction such as steel manufacturing and infrastructure construction. However, the OBOR initiative is a broad initiative and captures everything from regional arts festivals and book fairs through to the establishment of the $100 billion Asian Infrastructure Investment Bank (AIIB), the $100 billion BRICS New Development Bank and the $40 billion Silk Road Infrastructure Fund. In March 2015 China’s National Development and Reform Commission (NDRC), Ministry of Foreign Affairs and Ministry of Commerce jointly issued the Visions and Actions on Jointly Building Silk Road Economic Belt and 21st Centruy Maritime Silk Road ('Visions and Actions Plan') for the OBOR initiative, which, similar to a strategy paper, acknowledges that the OBOR is a pluralistic and open process of co-operation which can be highly flexible and does not seek conformity.
However, at its core OBOR demonstrates a high level political commitment in China to work with participating countries to facilitate an increase in trade and investment flows and interconnections. A key focus of this is on reducing barriers to trade – both overcoming literal barriers (such as inadequate port, rail and road infrastructure) and also overcoming less tangible barriers (such as enhancing trade liberalisation and easing customs and quarantine processes).
OBOR calls for an improvement on the region’s infrastructure, with a call for greater energy and power interconnections and to establish a secure and efficient network of land, sea and air passages across the key routes. Additionally, the initiative calls for greater policy co-ordination (such as opening free trade areas and improving co-operation in new technologies) and financial integration (such as carrying out multilateral financial co-operation in the form of syndicated loans and supporting foreign countries to issue RMB denominated bonds). Furthermore, whilst the OBOR is firmly rooted in the Silk Road’s thousand year old heritage, it also clearly looking to the future – greater e-commerce interconnectivity and advancing the construction of fibre optic cables is encouraged.
OBOR: 2+ years down the road
Since OBOR’s 2013 launch, we have seen the successful launch of the Asian Infrastructure Investment Bank (AIIB), the $100 billion BRICS New Development Bank and the $40 billion Silk Road Infrastructure Fund (SRF). The former two institutions (AIIB and BRICS New Development Bank) are not exclusively directed towards the OBOR (although they are indeed relevant), but the latter, SRF, as the name suggests, has OBOR projects as a prime focus. Moreover the SRF has already started being a particularly active investor along the OBOR routes. For example, in April 2015 the SRF announced its first OBOR investment project – Pakistan’s 720-MW Karot hydropower project. In June 2015, the SRF (together with one of China’s largest chemical enterprises, ChemChina) announced agreements to seek to acquire Italian tyre manufacturer Pirelli. In September 2015, SRF concluded a framework agreement with one of Russia’s leading independent gas producer, Novatek, on the acquisition by SRF of a 9.9% equity stake in the Yamal LNG project. The SRF has also been an active investor in recent Hong Kong initial public offerings, taking cornerstone stakes in each of China International Capital Corporation’s October 2015 IPO and China Energy Engineering Corporation’s November 2015 IPO.
Other projects announced in connection with the initiative include a number of private Chinese companies’ foreign expansion and joint venture plans in a OBOR countries, such as the strategic co-operation agreement between Anhui Conch Cement and the Bank of China to see Anhui Conch Cement investing to establish new project sites in South East Asia; and machinery maker XCMG Group’s opening of new joint venture factories in Uzbekistan.
Additionally, Chinese regulators have continued to lay the regulatory and diplomatic foundations to support the OBOR initiative. Domestically, under the guidance of the March 2015 of the Visions and Actions Plan (which lays out the broad strategy of the initiative (see above)), 2015 saw other key Chinese regulators issue supporting guidance. This included China’s State Administration of Taxation releasing the 'Notice Regarding the Tax Services and Administration to Implement the Development Strategy of the ‘One Belt One Road’' regarding tax services and improvements contemplated for the OBOR route and the Ministry of Transport drafting supporting plans and measures. Additionally a number of Chinese provinces have published guidance notes and plans relevant to their local areas, for example Guangdong (June 2015); Hunan (August 2015); and Henan (December 2015). Each of these localised plans focuses on the geographical benefits and respective strengths of each province. For example the Guangdong plan focuses on developing shipping and cross-boundary infrastructure in the Pearl River Delta (covering the Guangdong-Shenzhen-Hong Kong and Macau bay area); whilst the inland province of Henan plans on positioning itself as an access point for the opening up of China's inland regions to the outside world.
On the international front, China’s diplomats have been busily engaging with relevant counterparties, with international agreements or memoranda issued jointly with countries as diverse as India, Hungary, Kazakhstan and Russia.
Successfully utilising OBOR opportunities
A large portion of China’s foreign investment and trade going forward are expected to take place in OBOR countries. However, the OBOR is not only outward looking from China - it is a two-way street, with the Visions and Actions Plan specifically welcoming companies from all countries to invest in China whilst also encouraging Chinese companies to participate in infrastructure construction and undertake other investments in other countries along the route.
Key industries for the OBOR initiative include: infrastructure and projects; energy and power; transport and logistics; information technology and industrial development; and financial markets.
Successfully implementing projects along the OBOR will not be without risks and challenges. Overcoming these risks will require thorough due diligence exercises and robust partnership and joint venture arrangements. More importantly success will depend on enterprises finding the right partners and having the right support networks providing a thorough understanding of local conditions, regulators, market players and, more generally “ways of doing business” in both China and the foreign host jurisdictions. This will be essential to be able to adequately identify, quantify and overcome risks and opportunities; to achieve this, an on the ground presence and knowledge of suitable partners and relevant contacts (both for foreign parties in China; and for Chinese parties in the foreign jurisdiction) is a perquisite.
Importantly, whilst China has allocated significant capital and resources towards implementing OBOR, China cannot implement the OBOR alone. Success of this initiative requires co-operation between Chinese enterprises and foreign counterparties in a raft of sectors and regions, covering everything from small scale trade and investment, to the delivery of large scale multi-jurisdictional game-changing infrastructure... and consequently the OBOR initiative offers countless opportunities for foreign companies to partner with Chinese companies, enterprises and financial institutions.
Please click to view this article on the DLA Piper’s website.
Editor's picks
Trending articles
Treading softly along China’s “One Belt, One Road”
By Julian Vella (Asia Pacific Head of Global Infrastructure, KPMG International)
China’s bold vision can make a significant contribution to bridging the Asian infrastructure investment gap. But Chinese investors should be aware of the heightened expectations that come with selecting and managing projects in new markets.
Over 2000 years ago, the Silk Road was established as a trade route connecting China with Eurasia and the mighty Roman Empire. The road, in various forms, lasted over 1500 years before a decline in political powers ended its influence. Fast-forward half a millennium, and China’s plan to rebuild its old trade links with Europe and Asia has aroused renewed excitement.
The “One Belt, One Road” initiative envisages a path by land from China through Central Asia to Europe, with the maritime route flowing through Southeast Asia, the Indian Ocean, the Middle East, and Africa to Southern Europe.
By building essential infrastructure and boosting financial and trade links, the belt and road aims to enhance commerce and spread prosperity across 60-plus countries with a combined population well in excess of 4 billion. Financing comes from a number of sources, such as the Asian Infrastructure Investment Bank (AIIB), the Bank of China, The China International Trust & Investment Corporation, (Citic), and the Silk Road infrastructure fund. To date, approximately 250 billion dollars (US$) of related projects have been contracted, much of them involving Chinese machinery, raw materials and construction firms.[1]
Choosing the right projects
Given its huge domestic development in recent decades, China is hardly a newcomer to managing major projects. However, taking its infrastructure show on the road, across such a diverse range of countries, raises a number of fresh challenges.
Firstly there is the sensitive issue of sovereignty. With China emphasizing that it will respect sovereign rights, project selection will in many cases be at the discretion of each of the nations along the route – whose priorities may or may not align with those of China. A proposed railway line that stretches through to Thailand, for example, could support the latter’s ambitions to become a regional logistics hub, and the former’s need to access key export markets, offering a win-win for both countries. On the other hand, some prospective projects could potentially be viewed as primarily benefiting either China (e.g. by securing its energy resources) or the country in question (e.g. building local infrastructure unrelated to the One Belt route). Under any circumstances, choosing the right projects to prioritize can be quite a challenge. When dealing with governments inexperienced in infrastructure development this is compounded, particularly as project selection can often become highly politicized. When you factor in concerns over lack of transparency, corruption, an uncertain legal and regulatory environment, unpredictable financial systems and foreign exchange exposure risks, then decisions become even more complex. China’s domestic infrastructure program has been largely government financed, and carried out at breathtaking pace to accelerate economic growth. Conducting projects outside of its borders, in emerging markets, is a far more complex and prolonged affair, with the involvement of an array of stakeholders, which can slow the pace considerably.
These issues make it doubly difficult to please financiers (either banks or funds), who expect a good return on their investment through carefully chosen, efficient and well-managed projects. Project leaders, must, therefore, show a high level of understanding of the unique regulatory, political, legal, financial and project risks associated with potential projects, such as resource nationalism, transparency and labor unrest. It’s especially important to earn a ‘social license to operate’ by creating a good working environment, contributing to communities and minimizing the carbon footprint.
Amidst this complexity, China should, therefore, exert ‘soft’ power through comprehensive and early engagement with all governments along the route, to ensure that every project is positioned as a collaborative venture that brings rewards to all parties. This may involve investment in areas of infrastructure that do not directly benefit China, such as healthcare, education and housing.
A new game with different rules
Chinese businesses have relatively less experience in managing overseas projects, except where they are directly tied to China’s economic and trade objectives. This opens up opportunities for players from more mature infrastructure markets such as Australia, UK and Canada, to offer new ideas and technical knowledge as part of their project development and project management support. With its recent US$880 million acquisition of Australian construction giant John Holland, The China Communications Construction Company (CCCC) has gained access to invaluable technical expertise; a move that could be replicated.
Hong Kong also has a significant role to play in supporting infrastructure development as well as facilitating trade and investment along the belt and road given its location, its connectivity with mainland China, and its strength in financial services, transport and logistics, and professional services.
In addition, Chinese investors must also acknowledge that some of the countries in the proposed route have traditionally strong links to other nations with a vested interest in the region, and may resist China’s overtures. Equally these powers, namely Japan, India and especially Russia (which has a big influence in central Asia) may not support China’s efforts, and could seek alternative trade routes and blocs. Japan has not signed up to the AIIB, having nailed its colors to the mast of the established Asian Development Bank (ADB) as one of the largest shareholders. Since the One Belt announcement, Japan has stepped up its game, pledging to increase its investment in the ADB by US$110 billion over 5 years, with an expressed intent to build infrastructure such as roads and railways while reducing pollution.[2]
India, meanwhile, has its own programs, namely the Spice Route between Asia and Europe, and the ‘Mausam’ project that revives ties with its ancient trade partners via the Indian Ocean, stretching from east Africa, along the Arabian Peninsula, past southern Iran to South Asia, Sri Lanka and Southeast Asia.
While commentators have sought to describe the “One Belt, One Road” in various ways, it is clear that the initiative does reflect the Chinese government’s recognition that its own prospects are inextricably linked with those of its trading partners, and that it must take a more global role to further these ambitions.
With an annual Asian infrastructure gap estimated to be US$800 billion[3], there is plenty of room at the table for the AIIB, the ADB, and, indeed, other interested investors from around the world. The ADB has said that it is prepared to co-operate with China and has welcomed the entry to the region of new institutions for funding and supporting development projects. Despite fears that the main players are trying to assert an unhealthy influence, their combined efforts can make a real contribution to sustainable, inclusive growth for dozens of emerging economies.
Please click to download the original PDF file on KPMG’s website.
[1] China’s ‘One Belt, One Road’ looks to take construction binge offshore, Reuters, 6 September 2015.
[2] Japan unveils US$110 billion plan to fund Asia infrastructure, eye on AIIB, Reuters, 21 May 2015.
[3] Building China’s “One Belt, One Road,” Center for Strategic & International Studies, 3 April 2015.
Editor's picks
Trending articles
Estonia: A Switched-on, Tech-Savvy Baltic Partner
While having the smallest population of the three Baltic States, Estonia is nevertheless the region’s ICT powerhouse, besides being one globally in many ways too. Innovative e-solutions and the omnipresence of high-speed internet and wi-fi services are good examples of how a tiny, post-Soviet nation has created the enabling conditions for an information society. This goes hand in hand with its strategic location in terms of regional logistics and Eurasian connectivity.
Given its small domestic market, innovative Estonian companies with ambitions to grow have to go beyond the country’s borders for development and expansion. Hong Kong can therefore be an ideal catalyst for Estonian companies that wish to exploit opportunities in Asia, especially under the umbrella of the Belt and Road Initiative (BRI).
Estonia as E-stonia
Among the three Baltic States, Estonia is the richest in terms of per-capita GDP, and also the highest ranking in the United Nations’ Human Development Index. Thanks to a forward-thinking government, a pro-active ICT sector and a switched-on, tech-savvy population, Estonia, a small country along the eastern shore of the Baltic Sea, has gained worldwide recognition for its digital economy. It has developed pioneering e-government initiatives, a high degree of cyber-security and groundbreaking e-solutions to daily life problems.
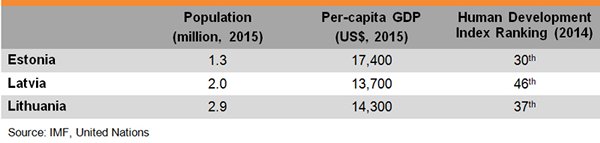
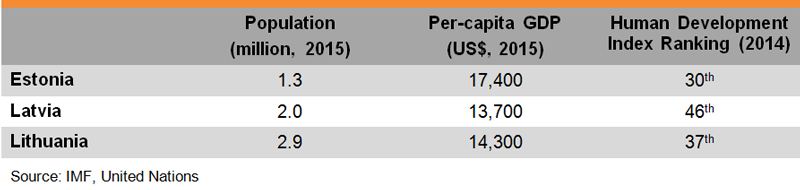
Even in Soviet times, radio-electronic and semi-conductor industries were well developed in Estonia. Following the formal declaration of independence in August 1991, the country underwent rapid economic transformation characterised by a favourable taxation system, free trade and large-scale privatisation.
The Estonian government has been very supportive of the country’s ICT industry and the country hosts both the NATO Cooperative Cyber Defence Centre of Excellence and the new headquarters of the European Agency “for the operational management of large-scale IT systems in the area of freedom, security and justice”, EU-LISA. Deeming it a basic human right, the government also made free wi-fi the norm throughout the country back in 2000. And it has incorporated data privacy and security protections into national laws to bolster long-term technology development and future ICT advances.
From developing the code behind Skype, Hotmail and Kazaa (a peer-to-peer file sharing application) to numerous e-government initiatives, Estonia continues to excel in terms of next-generation e-solutions that make a difference at a grassroots level, connecting people with people, with the state and with the wider world. As a member of Digital 5 (D5), a network of digital governments who share the goal of strengthening the digital economy, Estonia (together with Australia, Singapore, South Korea and the UK) presents a wealth of possibilities not only for business, but also for cooperation between governments and between business and government in the era of e-government.
Nowadays, 99% of bank transfers are performed electronically in Estonia, where many young people have never seen a cheque or cheque book in their lives, while 95% of income taxpayers file their annual tax returns online. In addition to banking and taxation, 98% of medicines are prescribed electronically and 66% of the population participated in the country’s last census online. As the world’s first country to allow online voting in a general election, in 2007, more than 30% of votes cast by Estonians in the 2014 EU Parliament elections were done so online.
Also in 2014, Estonia became the first country in the world to offer e-residency — a transnational digital identity. With 10 million e-residents targeted by 2025, it is open to anyone in the world interested in administering a business online. E-residents can sign and verify documents and contracts digitally, conduct e-banking, make remote money transfers and pay Estonian taxes online. They can effectively run an Estonian company online and administer it from anywhere in the world.
The e-residency and its embedded digital signature allows people to perform most business and personal transactions online, except for marriage, divorce and sales of property. This initiative is a big help to many international financial and technology companies looking for new platforms or markets in which to conduct R&D. Since May 2015, Estonia has allowed online e-resident applications and payment for a smart ID card. So far, the initiative has been best received by applicants from Finland, Russia and the US – countries where Estonian ICT and knowledge-based companies are accustomed to seeking out partners and venture capital.
Strong ICT Sector and Strategic Location
In ancient times, goods bound for Scandinavia which had travelled the Silk Road went through Estonia. In addition to its distinct geopolitical location, Estonia is again proving an increasingly important logistics platform for moving goods, knowledge and people from east to west. Combined with the country’s strong ICT background, this makes Estonia a ready candidate for greater regional and inter-regional integration, in keeping with the BRI.
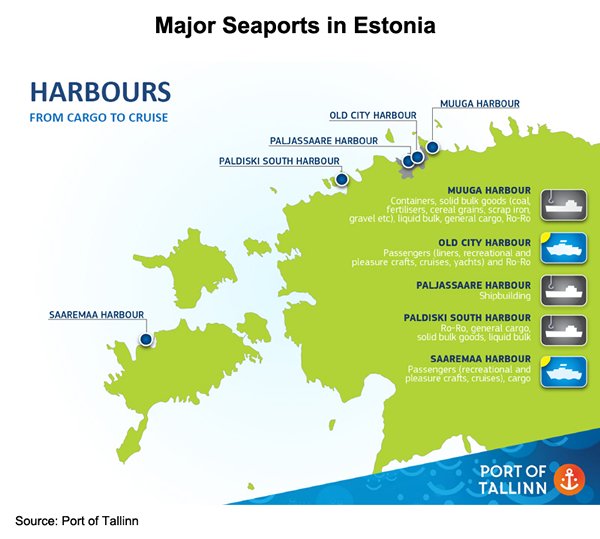
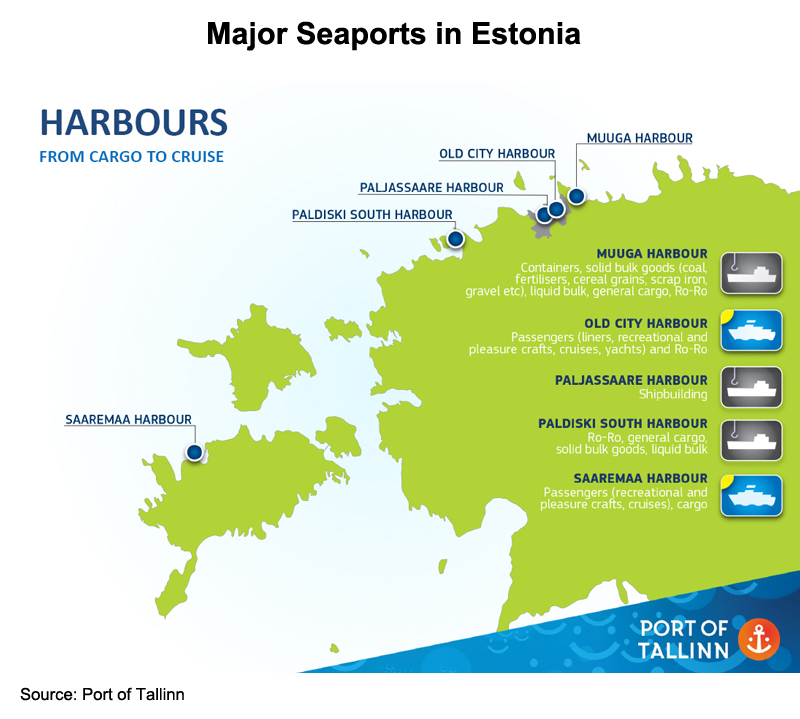
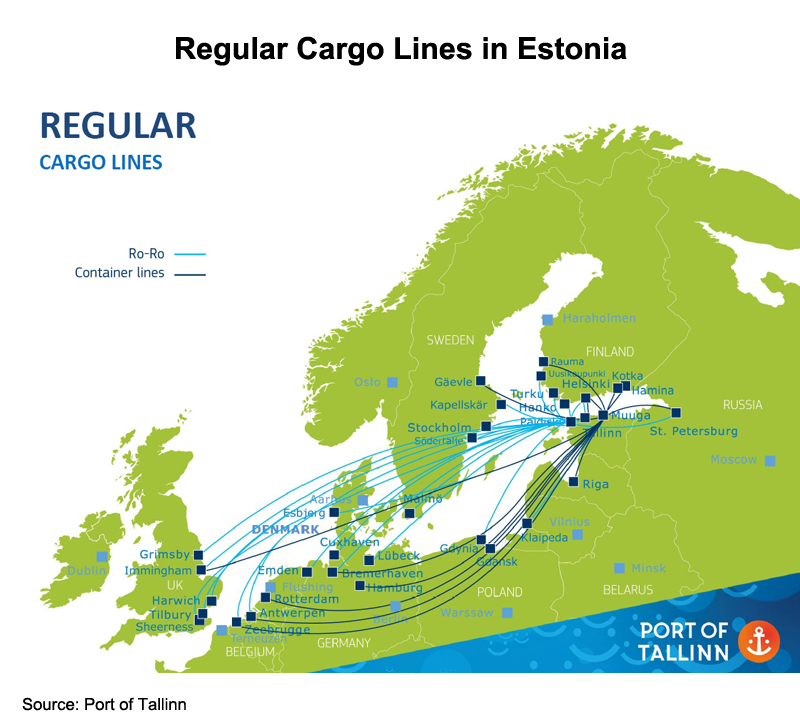
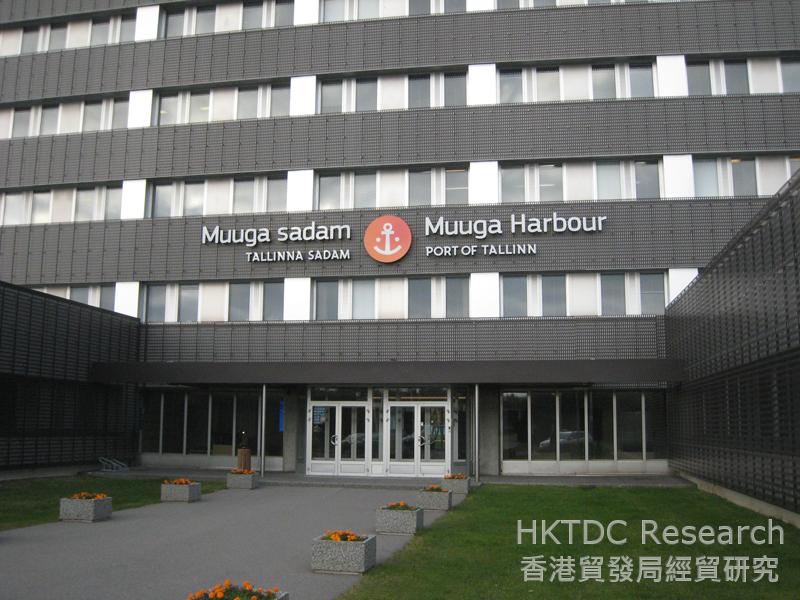
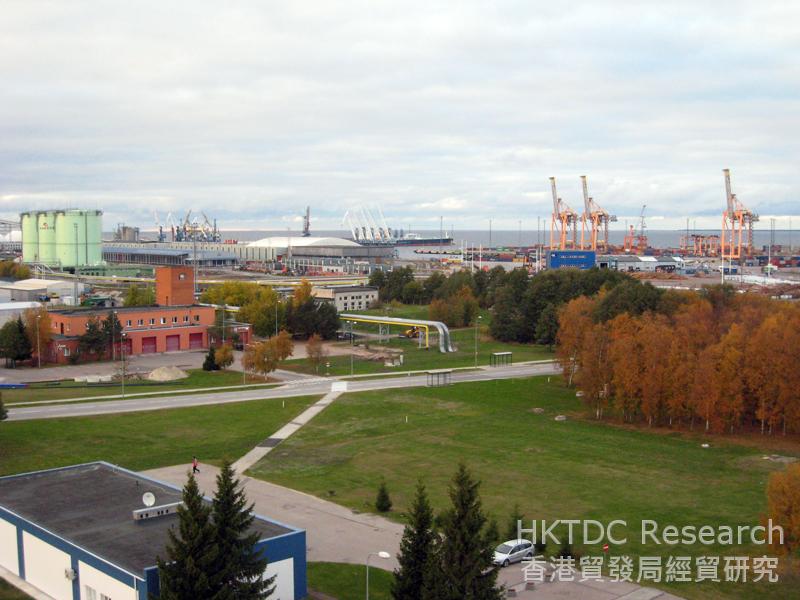
Situated on a busy trading route between East and West, Estonia operates nearly 30 well-developed ports. Among them, the five harbours (Old City Harbor, Muuga Harbour, Paldiski South Harbour, Paljassaare Harbour and Saaremaa Harbour) operated under the umbrella of the state-owned Port of Tallinn (a port authority rather than a single seaport) constitute the nearest Baltic ports to Russia (apart from the exclave of Kaliningrad, which is surrounded by Poland and Lithuania). Altogether the Port of Tallinn handled 22.4 million tonnes of cargo, 208,784 containers and 9.8 million passengers in 2015, when 1,684 cargo ships and 5,397 passenger ships called in.
With the aim of connecting the peripheral Baltic States to “the heart of Europe”, the European Commission in 2004 initiated Rail Baltica, a strategic project linking Estonia (Tallinn), Latvia (Riga), Lithuania (Kaunas, Vilnius) and Poland (Warsaw), with the route also set to be extended to countries such as Germany (Berlin) and Italy (Venice) in the future. Rail Baltica is a Trans-European Transport Networks (TEN-T) Priority Project.
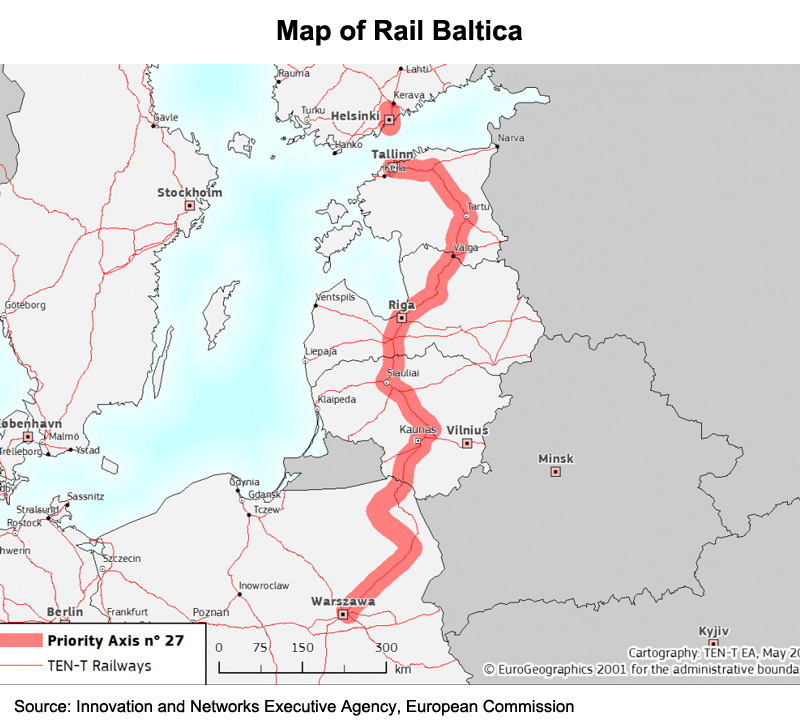
It is also the first step in the Baltic countries’ transition to European railway-gauge standards. With road transport accounting for more than 97% of total cargo flows between the Baltic States and Poland, it creates the possibility to shift the heavy freight traffic between Estonia, Latvia, Lithuania and the rest of EU from road to rail, in turn helping to reduce commuting times, traffic congestion and air pollution. With the signing of a memorandum of understanding (MOU) on 5 January 2016 to build a 92km underwater tunnel connecting Tallinn and Helsinki, for example, the commuting time will be slashed by 70%, from 100 minutes to 30 minutes, upon completion.
As regards air transport, Estonia recently earmarked €40.7 million (or HK$346 million) as initial capital for a new, fully state-owned carrier, after the ailing Estonian Air was found to be in breach of the EU’s state-aid rules and ceased operations as of 7 November 2015. Estonia also plans to team up with regional air hubs such as Helsinki in Finland for more regional air services cooperation. This will help compensate for the loss of business due to Estonia Air’s wind down, while also enhancing the country’s air connectivity for both freight and passengers.
Together with its strong ICT background and infrastructure, Estonia’s strategic location and enhanced multimodal connectivity provide a fertile breeding ground for cross-border e-commerce businesses. In September 2015, the state-owned Estonian postal company, OMNIVA, signed an MOU with S.F. Express, China’s largest private-capital-funded courier company, to set up a joint venture called Post11. This includes warehouses in Estonia to make the import and export of goods between China and Europe faster and more efficient. The joint venture will first focus on the delivery of goods from China to the Baltic States, Russia, Ukraine and the Scandinavian countries, before extending its reach to the whole of Europe.
With nearly half of all the goods Estonians order from abroad coming from China, the joint venture and its new supply chain solutions will likely strengthen Sino-Estonian and Sino-European e-commerce as cooperation between Chinese e-stores and Estonian ICT and logistics solutions becomes more seamless.
Ready for the BRI
Constrained by its small population, Estonia is no longer positioning itself as an ICT manufacturer as it did during the Soviet times. Boasting one of the world’s highest per-capita business start-up ratios, it is, however, aiming to strengthen a dynamic and competitive knowledge-based economy, providing an environment for ongoing digital success stories.
Hong Kong, as Asia’s top IP and technology marketplace, can be an ideal trading platform for Estonian technology and innovative e-solutions. Its easy access to equity financing and its robust legal and IP regimes can also help Estonian startups looking for venture capital, local business opportunities and strategic partners.
As a pioneer in cyber-security and many e-government initiatives, Estonia has companies which can be ready partners for Hong Kong’s professional services providers and financial institutions, especially with regard to the development of FinTech. It is reported that one Russian company is looking to connect Estonian tech startups with investors from Asia via Hong Kong, while also marketing their technology and practical e-solutions to big financial services clients located and headquartered in the city.
Aside from technology and financial opportunities, Estonia’s ongoing improvement in its multimodal connectivity is also conducive to the successful implementation of the BRI, which aims to facilitate and promote greater integration among the 60-plus countries along the Belt and Road. The economic ties between Estonia and China will also be strengthened through membership of the “16+1” formula [1].
Hong Kong’s connectivity with much of Asia, its privileged free-port status and its cost-effective multimodal logistics options are helping Estonian companies reach out to Asia. This role will be further strengthened as the Second Eurasian Land Bridge takes shape and new railway routes are established. In particular, the recent opening in Hong Kong of the development office of KTZ Express, a wholly-owned subsidiary of Kazakhstan Railways, in order to promote multimodal freight logistics through Kazakhstan between Europe and China, indicates the city’s key role in Belt and Road logistics.
[1]In 2011, China revived its cooperation with a group of 16 Central and Eastern European (CEE) countries: Estonia, Latvia, Lithuania, Poland, the Czech Republic, Slovakia, Hungary, Romania, Bulgaria, Slovenia, Croatia, Serbia, Bosnia and Herzegovina, Montenegro, Albania and Macedonia. In 2012, the first meeting at the level of heads of government was held in Warsaw, marking the official launch of the “16+1” formula.
| Content provided by |

|
Editor's picks
Trending articles
A Belt and Road Development Story: Trade between Xinjiang and Central Asia
Geographically, Xinjiang borders a number of Central Asian countries, including Kazakhstan and Kyrgyzstan. With improved transportation and access, Xinjiang's ports have become China's coastal and central regions’ gateways for export to Central Asia. According to Xinjiang's customs statistics, the freight volume of its ports increased from 20.93 million tonnes in 2009 to 46.65 million tonnes in 2014, while the total value of their imports and exports soared from US$22.29 billion in 2009 to US$46.14 billion in 2014.
A Vital Role in China’s Trade with Central Asia
Besides functioning as a transportation channel, Xinjiang also serves as a trading platform for Chinese goods destined for Central Asia. Although market demand in Central Asia weakened in 2015 due to economic, exchange rate and other factors, Xinjiang's exports of light industrial products, machinery and electronic products, as well as of processed food, continued to grow thanks to rising demand for Chinese products in the Central Asian markets over the last few years. In addition to local products, buyers from Central Asia are also eager to source goods manufactured in other parts of China, including the Yangtze River Delta and Pearl River Delta regions. This makes Xinjiang a trading platform for sales to Central Asia.
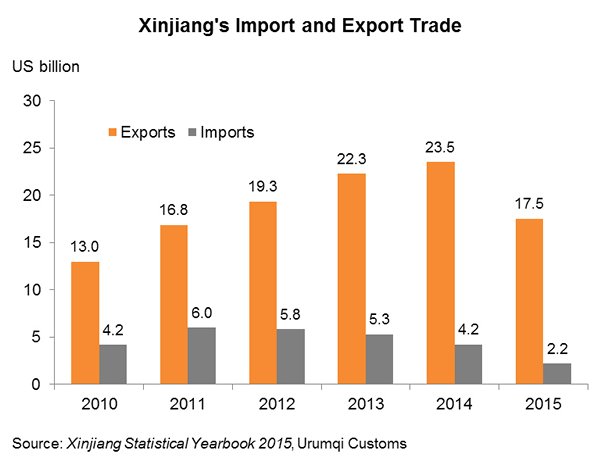
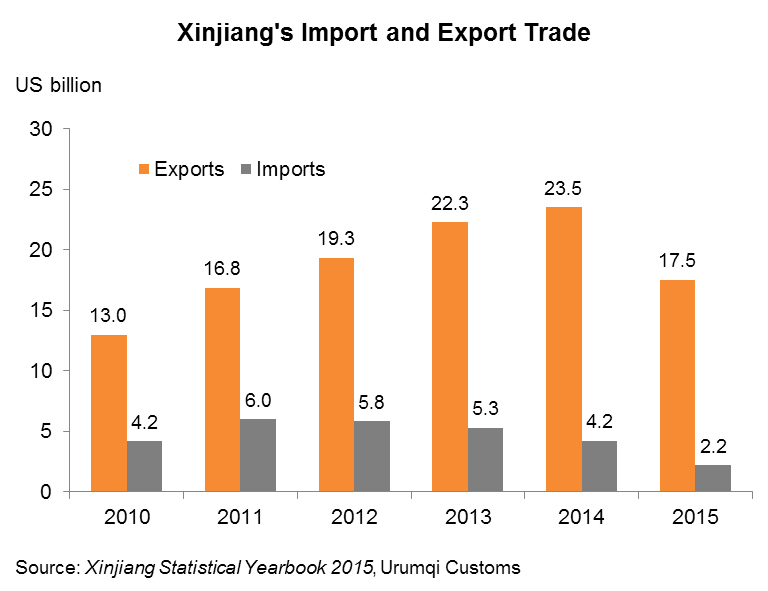
Xinjiang mainly trades with the Central Asian countries. Customs statistics show that as a result of falling demand in Central Asia, Xinjiang's total import and export value dropped to US$19.68 billion in 2015. However, the fact that import/export trade with Kazakhstan and Kyrgyzstan still accounted for 46% of Xinjiang's total trade value and Xinjiang's trade with Central Asian countries still accounted for a big share of China's trade with these countries suggests that most of China's trade with Central Asia uses Xinjiang as an intermediary. It also indicates that most of the export goods come from China's coastal or inland areas.
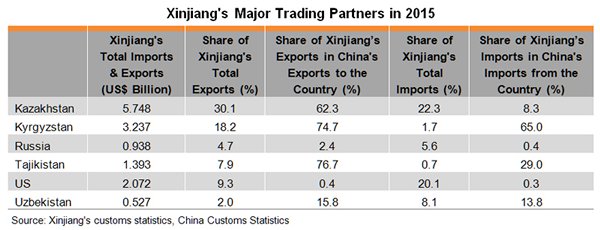
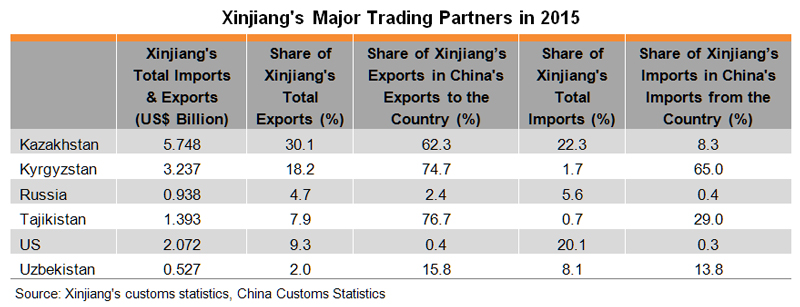
A large proportion of China's exports to Central Asian countries are handled by companies in Xinjiang, including both local firms and agents of other mainland enterprises. In 2015, Xinjiang's exports to Kazakhstan, Kyrgyzstan and Tajikistan accounted for 62.3%, 74.7% and 76.7%, respectively, of China's exports to these three markets, reflecting Xinjiang's crucial role in China's trade with Central Asia.
“Border Trade” the Prevalent Format
“Border trade”, or “petty trade in border areas”, is the principal form of trade in Xinjiang. In the wake of economic growth in the neighbouring Central Asian countries, many trading firms in Xinjiang are expanding their business in those markets through "border trade". Exports through "border trade" include cotton/textile products, agricultural products and processed foods, as well as consumer and industrial goods sourced from other provinces or produced in collaboration with manufacturers in these provinces for export to Central Asia through Xinjiang.
"Border trade" in Xinjiang refers to import/export trade conducted by enterprises registered in Xinjiang with the government's foreign trade/commerce authorities and thereby qualified to trade with enterprises or other trading organs in Xinjiang's “neighbouring” countries – that is, countries bordering on Xinjiang, via Xinjiang's designated land ports. “General trade” refers to import/export trade conducted by all countries through Xinjiang or other ports of China. In other words, enterprises with the relevant qualifications may conduct trade in the form of "border trade" when trading with neighbouring countries such as Kazakhstan but must conduct trade in the form of "general trade" when trading with non-neighbouring states.
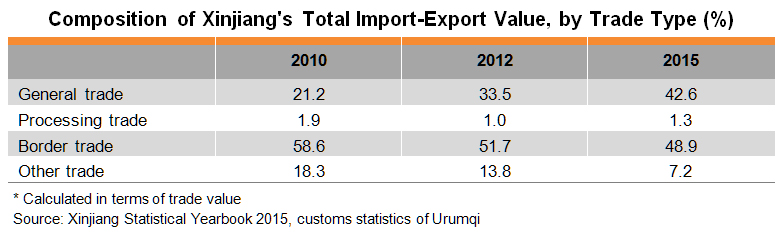
Although "border trade" still accounts for the lion's share of Xinjiang's import/export trade, as an official of Xinjiang's department of commerce pointed out, some of the preferential policies for border trade have been abolished and there is a movement in the direction of general trade. In fact, as can be seen from Xinjiang's import/export trade statistics, border trade dropped from 58.6% of total trade in 2010 to 48.9% in 2015, while general trade has soared from 21.2% in 2010 to 42.6% in 2015.
Shopping Malls as Trade Platforms
Geographically, Xinjiang borders a number of Central Asian countries. Culturally, Xinjiang’s Uyghur population and other minorities have similar customs and habits to people in Central Asia. Border inhabitants’ petty trade ties with neighbouring countries are long-established. Xinjiang's export companies are mainly found in Urumqi and border ports such as Yining and Khorgas, with Urumqi as their top choice.
Urumqi boasts a variety of wholesale markets, where traders from other provinces have set up shop. They attract merchandisers not just from Urumqi and other domestic markets in northwestern China but also others engaged in border trade between Xinjiang and Central Asia. Many of the shops in these markets are opened by merchants from Zhejiang province, for example. An operator of a wholesale market in Xinjiang estimates that over 100,000 people from Wenzhou, Zhejiang, are conducting business in these markets and that at one stage between 200,000 and 300,000 people from Wenzhou were to be found in Xinjiang, although that number has since fallen somewhat.
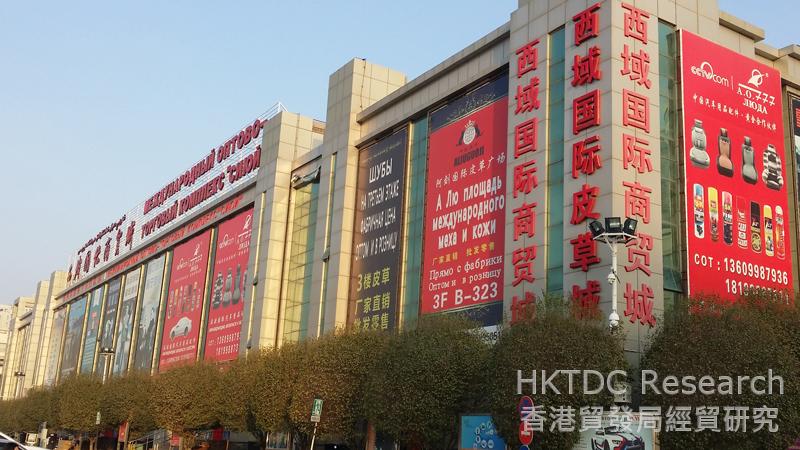
These wholesale markets deal in all kinds of goods. For example, Urumqi’s Bianjiang Hotel international trade city mainly deals in garments, shoes, headwear and other light industrial goods. The Diwang international mall, Dehui trade city and Huochetou foreign trade wholesale market mainly deal in garments, shoes, headwear and fashion accessories. The Xinjiang small commodity city sells furniture, bags/luggage and home appliances. Hualing comprehensive market mainly deals in building materials and furniture, while the Xiyu international trade city specialises in auto parts, tyres and automotive cosmetic products.
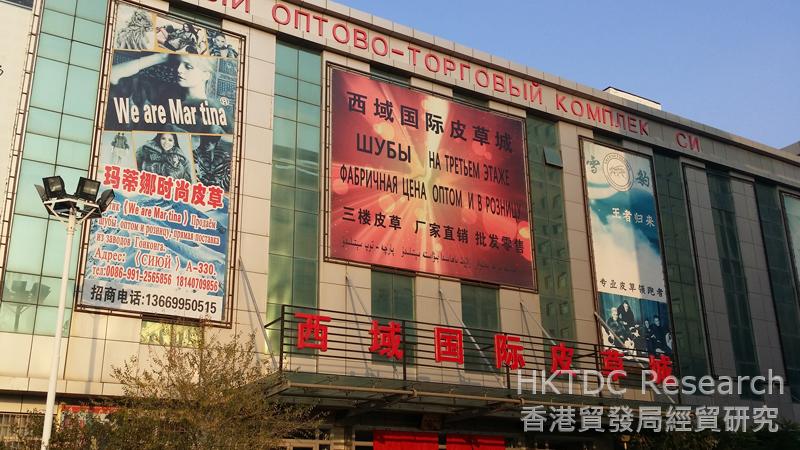
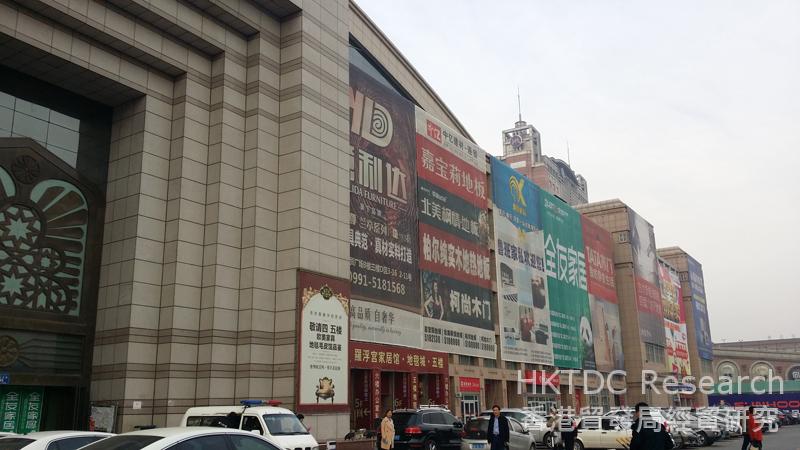
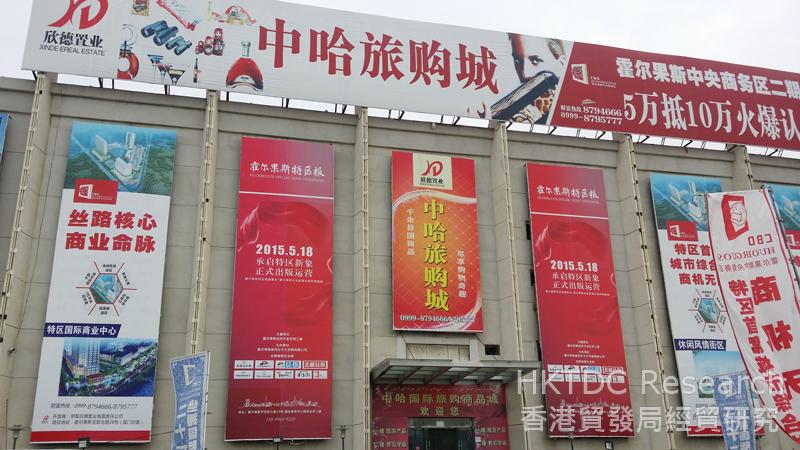
Some of these wholesale markets are very large. For example, the Hualing comprehensive market has three buildings and houses about 10,000 businesses from all over the country. Daily visitor traffic is said to average around 100,000 and the goods are sold to Urumqi's neighbouring prefectures and counties and even exported to neighbouring countries such as Kazakhstan.
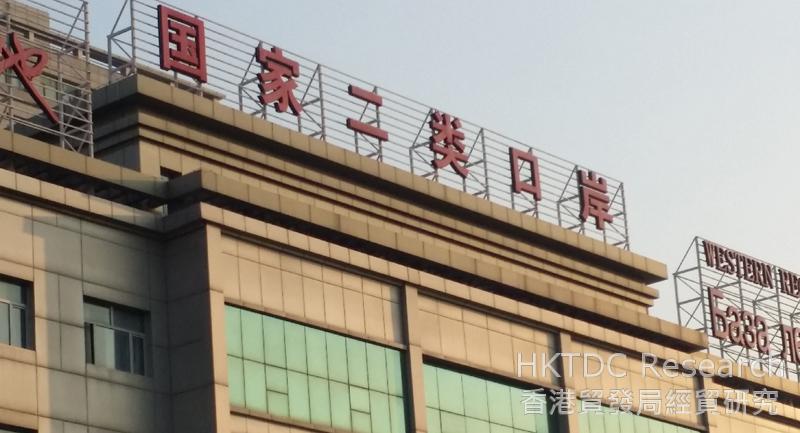
The Xiyu international trade city resembles a small commodity city in Yiwu, Zhejiang province, and has about 1,000 shops, most of which deal in auto parts, tyres and automotive cosmetic products. They essentially act as agents and frequently participate in exhibitions to find suitable suppliers. They have their own warehouses, which they use to store popular merchandise sourced from the coastal areas to meet market demand at any given time, although they may also make purchases on receiving orders. The period from June to August tends to be their off season. Buyers from Central Asia can stay for any length of time, from just a few days to several months at a time. The market has hotel rooms/apartments to meet their accommodation needs and it is understood that between 400,000 and 500,000 visitors stay in the hotels each year. The trade city also boasts logistics service providers, dedicated logistics parks and supporting customs services.
Challenges Facing Xinjiang's Foreign Trade
After many years of growth, Xinjiang's exports to Central Asia started to fall as market demand in the region, and China's exports overall, dropped in 2015. Xinjiang's exports dropped 25.4% in 2015, with exports to Kazakhstan and Kyrgyzstan dropping by 40.1% and 21.2% respectively, although exports to Russia rose by 37.5%. Economic cycles and shifts were partly responsible for reduced market demand in Kazakhstan. The falling price of oil and other commodities in recent years has directly affected the performance of the Kazakh and other Central Asian economies. Substantial currency devaluation in these countries has also weakened their purchasing power. Overall, China’s exports to Kazakhstan saw a drop of 33.8% in 2015.
Xinjiang's exports to Central Asia also face a number of structural challenges. Firstly, the influence of the Russia-Belarus-Kazakhstan Customs Union has weakened the competitiveness of China's export goods. The unification of import tariffs between these three countries has led to an increase in tariffs on goods imported by Kazakhstan from China. The union also encourages trade between member states, which has had a detrimental effect on imports from China. The deal has also led Kazakhstan to gradually improve customs clearance management for some “grey” imports. Meanwhile, some buyers from Central Asia have started to make purchases directly from Yiwu, Zhejiang province, thus impacting on Xinjiang's intermediary role.
Still a Role For Xinjiang as Trade Intermediary
One local trader told HKTDC Research that while some buyers from Central Asia had gone directly to inland and coastal cities to make purchases, some claimed to have had bad experiences in doing so – for example, they found the quality of goods was not what they paid for. For this reason, many buyers still preferred to make purchases through trusted middlemen. Central Asian buyers may also encounter language problems when making direct purchases, while mainland suppliers may not be able to provide all the required customs clearance services (including customs clearance for Kazakhstan). Xinjiang's trading companies, on the other hand, are in a position to offer one-stop services.
As a trade intermediary, Xinjiang has also started to develop in terms of offering online platforms. For example, the Yema Group, a large trading company in Xinjiang, plans to start B2C cross-border e-commerce with Central Asia by sourcing goods from the mainland and selling them, through Urumqi, to consumer markets in Central Asia and Russia. The group will mainly target Russia, followed by Kyrgyzstan, because it has Russian language expertise and has established logistics and payment systems in those markets.
Hong Kong companies interested in venturing into Central Asia should look for opportunities via Xinjiang's trading firms and relevant e-commerce platforms. Many companies have set up production facilities in Xinjiang’s economic and technological development zones, bonded areas and export processing zones. There they are able to make use of raw materials and semi-finished materials produced both locally and in other parts of China, and of raw materials and spare parts imported from Central Asia and other countries, for production and processing in Xinjiang and, ultimately, export to Central Asian markets. Hong Kong companies may alternatively look to partner with existing operations in this area.
| Content provided by |
|